Rapid Rescore Explained: How Mortgage Borrowers Raise Their Credit Score in Days, Not Months

Rapid Rescore Explained: How Mortgage Borrowers Raise Their Credit Score in Days, Not Months

Douglas Wilkerson
Published on: 02/11/2026

Rapid rescore: your mortgage lender can update your credit report in 3-5 business days after a real paydown or correction, instead of waiting for the next statement cycle. How it works, what it costs, and the dollars a crossed score band saves.

rapid rescoremortgage credit scorecredit utilizationFICO score bandsLLPAJacksonville homebuying
The Score on Your Phone Isn't the Score Your Lender Sees: How Mortgage Credit Pulls Actually Work

The Score on Your Phone Isn't the Score Your Lender Sees: How Mortgage Credit Pulls Actually Work

Douglas Wilkerson
Published on: 30/10/2026

Your free credit app shows a VantageScore. Your mortgage lender pulls Classic FICO from all three bureaus and uses the middle score. Here's why the numbers differ and what to do before you apply.

mortgage credit scoreVantageScore vs FICOClassic FICO mortgagetri-merge credit pullmiddle credit scoreJacksonville mortgagecredit score for mortgage
No Credit Score? You Can Still Get a Mortgage: How Thin-File Borrowers Qualify in Jacksonville

No Credit Score? You Can Still Get a Mortgage: How Thin-File Borrowers Qualify in Jacksonville

Douglas Wilkerson
Published on: 28/10/2026

Having no credit score is not the same as having bad credit. VA sets no minimum score at all, and FHA lets a lender build your history from rent and utility payments. What stops most thin-file buyers is one lender's overlay — not the agency rulebook.

no credit score mortgagethin file borrowerVA loan no credit scoreFHA non-traditional creditmanual underwritingrent payment history mortgageJacksonville first-time home buyer
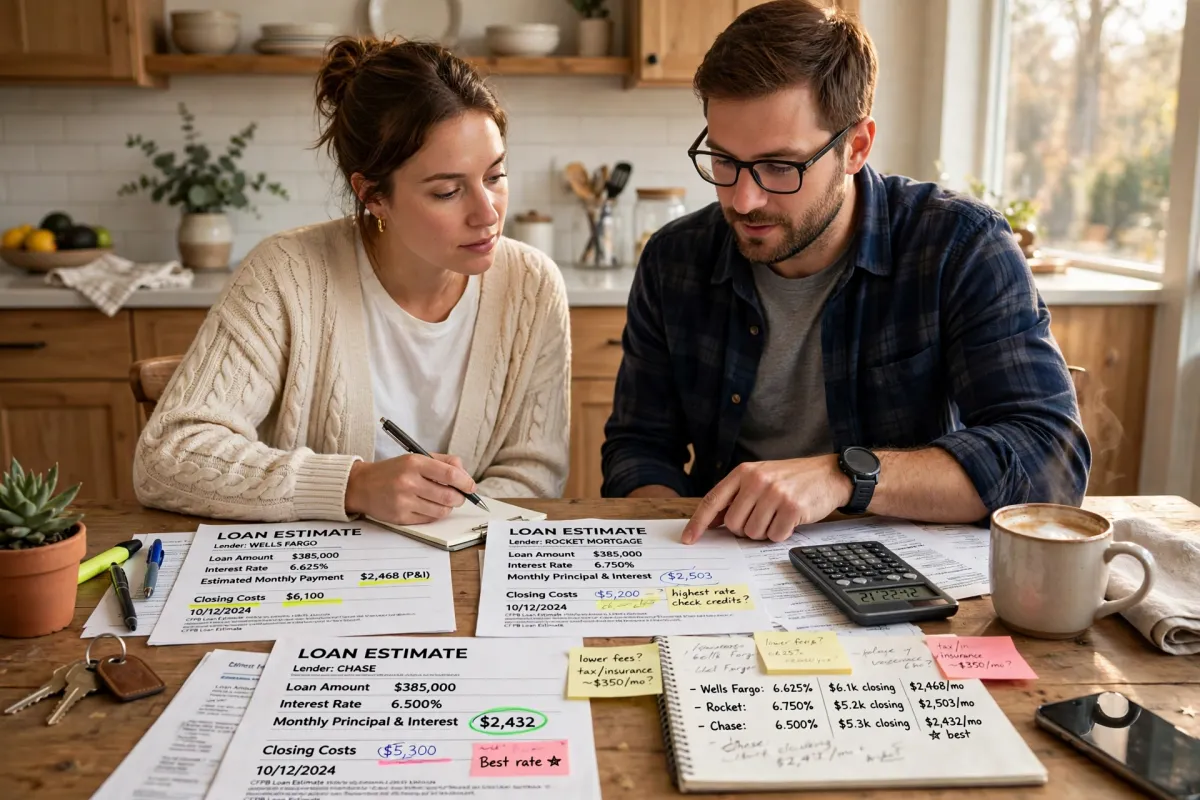
Shopping for a Mortgage Won't Wreck Your Credit Score: The 14-Day and 45-Day Windows, Explained

Shopping for a Mortgage Won't Wreck Your Credit Score: The 14-Day and 45-Day Windows, Explained

Douglas Wilkerson
Published on: 26/10/2026

Shopping for a mortgage does not cost you one credit hit per lender. FICO ignores mortgage inquiries from the 30 days before scoring and counts pulls inside a 14- or 45-day window as a single inquiry. Here is the 14-day plan that keeps you covered under every model.

mortgage rate shopping credit scorecredit inquiry mortgage applicationFICO rate shopping window 14 days 45 dayshard inquiry mortgage credit scorehow many lenders should I apply to mortgagecredit score mortgage shopping Jacksonvillesoft pull vs hard pull mortgagemortgage shopping window explained