Don't Touch Your Credit Between Application and Closing: The 7 Moves That Can Kill Your Mortgage Approval
The short answer: Your mortgage approval is a snapshot, not a promise. Between application and closing day, your lender runs soft-pull credit monitoring and re-verifies your employment — and new debt, a closed account, a job change, or an unresolved dispute can push your debt-to-income ratio over the program limit or drop your score enough to kill the approval days before funding. The safe rule: freeze your financial life until the keys are in your hand.
You got pre-approved, found the house, went under contract. But your loan file isn't frozen in time — your lender is watching it until the money moves.
I'm Douglas Wilkerson, a Mortgage Broker (NMLS #1680719) in Jacksonville, FL. I broker through 200+ lenders, working from the actual agency guidelines — Fannie Mae, Freddie Mac, FHA's HUD 4000.1, VA — not bank overlays. Most "my loan fell apart at closing" stories trace back to seven innocent-looking credit moves. Here they are, with the real rules and numbers.
Why Your Lender Is Still Watching Your Credit After You Apply
The CFPB lists three ordinary times a lender runs a credit check: when you apply, just before you close, and when managing existing accounts. That middle one isn't a formality.
Most lenders run undisclosed debt monitoring — automated soft-pull surveillance from application through closing that flags new tradelines, inquiries, balance changes, and DTI shifts, usually within a day. Equifax reports 46% of mortgage applicants submit other credit inquiries during this "quiet period." Fannie Mae and Freddie Mac require lenders to catch undisclosed debt before a loan can be sold — and anything the monitoring finds can force a full re-underwrite. The soft pull never affects your score. What it finds can still cost you the house.
For the week ended October 22, 2026, Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed at 7.32% and the 15-year at 6.68% (Oct 2026 — Douglas Wilkerson, NMLS #1680719). At these rates, a blown approval doesn't just delay you — it can price you out entirely.
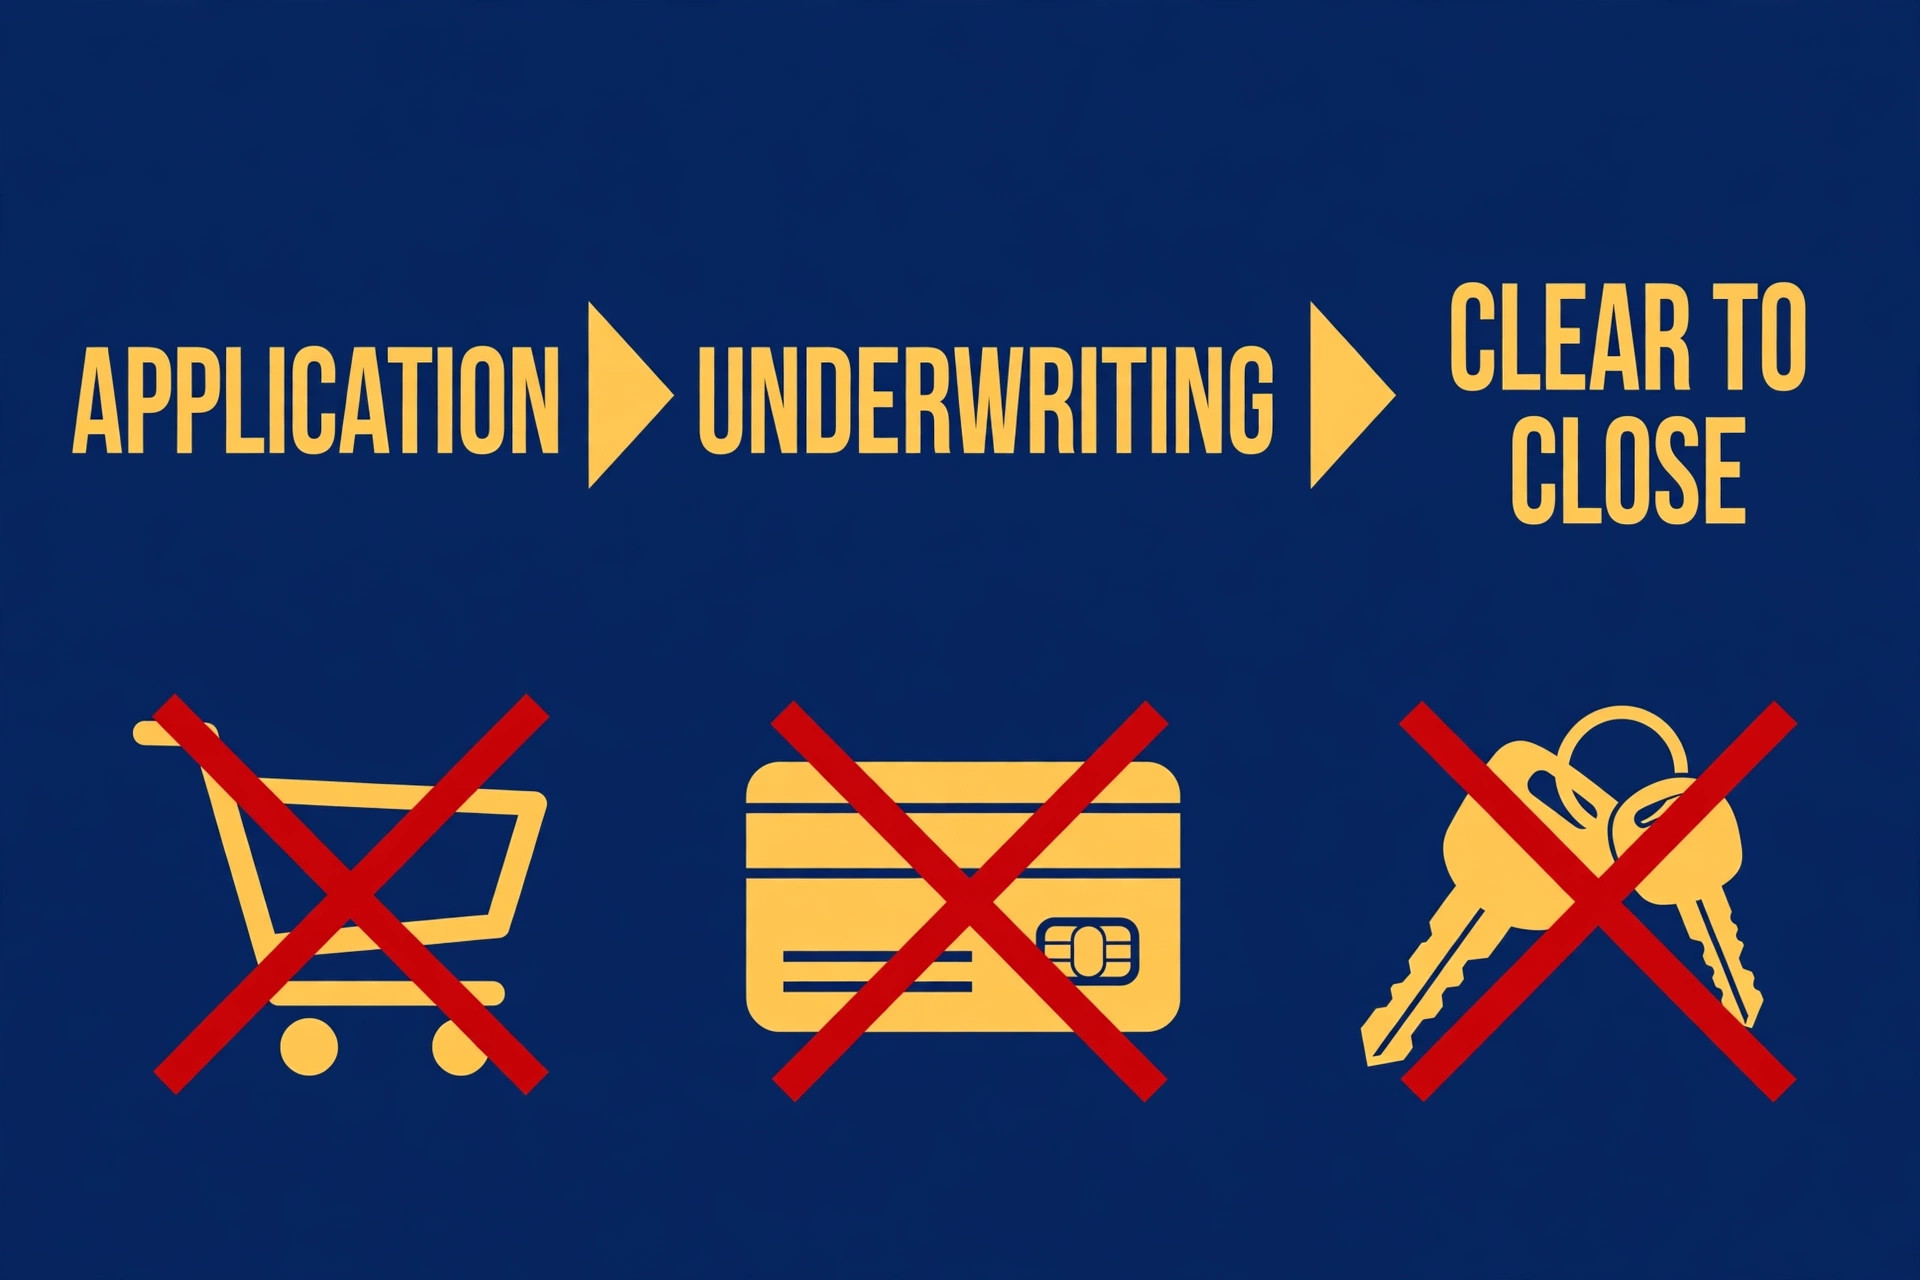
Move #1: Don't Open New Credit — Not Even a "No Payments for 12 Months" Store Card
The classic killer: you're under contract, a furniture store offers 12 months of no payments if you open their card. It feels free. It does three kinds of damage at once:
- A hard inquiry. Per FICO (via Experian), one hard inquiry typically costs fewer than five points — small, but on a borderline file that's the difference between approval and denial. Unlike mortgage rate-shopping — where FICO bundles multiple mortgage inquiries into one within the window (14 days on older models, 45 days on newer; VantageScore uses 14 days) — a store card counts as its own inquiry, every time.
- Score-factor damage. New credit is 10% of your FICO score, and a new account drags down your average account age, feeding the 15% "length of credit history" slice. (Per myFICO, payment history at 35% and amounts owed at 30% carry the most weight.)
- A new tradeline with a balance. That furniture purchase now shows up as a minimum payment inside your DTI — where approvals actually die (see Move #3).
Move #2: Don't Close Old Accounts (Yes, Even the Ones You Never Use)
Closing old cards to "simplify" can drop your score overnight. Utilization — balances divided by total available credit — lives inside the "amounts owed" slice of your FICO score (30%). Close a card and its limit vanishes while your balances stay put:
- Two cards, $5,000 limit each, $1,000 balance each: $2,000 ÷ $10,000 = 20% utilization.
- Close one card: $2,000 ÷ $5,000 = 40% utilization.
Same debt, twice the utilization — possibly days before your lender's final credit refresh. An old card with a zero balance is helping you. Leave it open at zero until after you own the house.
Move #3: Don't Finance the Furniture, the Appliances, or the Car
The most common approval-killer — pure DTI math. Every new monthly payment lands in your back-end debt-to-income ratio, and every program has a ceiling. These are the actual agency guidelines, not bank overlays:
- Conventional (Fannie Mae): 45% back-end DTI standard max, up to 50% via Desktop Underwriter only with strong compensating factors (reserves, credit).
- FHA: 31%/43% standard; TOTAL Scorecard can approve up to 46.9%/56.9% on an approve/eligible finding.
- VA: 41% DTI guideline — but residual income (cash left after obligations) is the real test; above 41%, VA wants residual income at least 20% over the regional minimum.
How fast a "small" purchase blows through those ceilings — $7,000/month income, $2,100 housing payment, $900 in other debts:
- Back-end DTI at application: ($2,100 + $900) ÷ $7,000 = 42.86% — approved, with room to spare.
- They finance furniture at $400/month before closing: ($2,100 + $900 + $400) ÷ $7,000 = 48.57% — over the 45% conventional ceiling. Approval dead, days before funding.
One $400 payment. "Buy now, pay later" plans report as new tradelines too — the underwriter will see them. Buy the furniture with cash after closing.
Move #4: Don't Co-Sign Anyone's Loan
Your kid needs a car, so you co-sign — and their monthly payment now counts against your mortgage DTI. Under Fannie Mae's Selling Guide, a co-signed debt is a contingent liability that stays in your ratio unless the other party made the last 12 months of payments with zero delinquencies, documented with 12 months of their canceled checks or bank statements. Not your word. Twelve months of paper.
Without that paper trail, the full payment lands in your DTI — enough to bust the ceiling from Move #3 on a tight file. FHA and VA have similar 12-month rules. Wait until after your closing to co-sign anything.
Move #5: Don't Make Large Deposits You Can't Paper-Trail
Selling stuff before a move is normal — but under Fannie Mae's Selling Guide, any single deposit over 50% of your total monthly qualifying income is a "large deposit" that must be sourced. Earn $7,000/month? Anything over $3,500 gets flagged. The usual tripwires:
- Cash — no paper trail by definition. A few thousand from a garage sale or a cash car sale can stall your file.
- Moving money between your own accounts, or via Zelle/Venmo/Cash App — still needs statements on both sides — payment apps read as mystery deposits.
Keep a bill of sale for anything you sell and every transfer receipt; never deposit cash you can't document. Gift funds are fine with a gift letter plus the donor's statements. When in doubt, call your loan officer before the deposit hits.
Move #6: Don't Change Jobs — and Definitely Don't Go Self-Employed Mid-File
Your income was approved based on your employment as disclosed on your application. Fannie Mae requires a verbal verification of employment within 10 business days before the note date — a call to your employer made as late as possible, specifically to catch changes. If it doesn't match your file, funding pauses.
The dangerous changes: quitting or switching employers even for more money (new verification, new pay stubs, possible re-underwrite); moving from salaried to contract, commission, or self-employed — self-employment income generally needs two years of tax returns averaged, so a great first month of freelancing counts for nearly nothing; any employment gap, even a short one.
Same line of work, stable or higher pay, properly documented — many files survive a job change. But a surprise at the verification call is a different problem. Call your loan officer before you accept, start, or leave anything.
Move #7: Don't Dispute Accounts Mid-Process — and Don't Let a Credit Freeze Block the Pull
Disputes: cleaning up your credit mid-file can backfire twice. On FHA loans, if the cumulative balance of your disputed derogatory accounts hits $1,000 or more, HUD 4000.1 forces a downgrade from the TOTAL Scorecard's automated approval to a Refer — manual underwriting. (Disputed accounts with zero balances, late payments 24+ months old, or accounts current and paid as agreed don't count toward the $1,000; medical and identity-theft disputes are excluded.) Worse, removing a dispute comment can drop your score once the account reports at full weight. Disputes are a before-you-apply or after-you-close activity. Major derogatory history has real, fixed waiting periods instead — I broke down the FHA waiting periods here.
Credit freezes: freezing your credit is smart, but your mortgage runs a tri-merge across all three bureaus — a freeze on even one blocks the pull and stalls your file. Temporarily lift the freeze at Equifax, Experian, and TransUnion for a set date range before each pull, then refreeze; it takes minutes online. If your score took a legitimate hit mid-process, here's how rapid rescores actually work — though the best strategy is never needing one.
What To Do Instead (the Short Version)
- Pay everything on time, every time — payment history is 35% of your FICO score, the biggest slice. One 30-day late during underwriting can kill a file.
- Pay balances down, not off-and-closed. Lower utilization helps; closed accounts hurt.
- Stay employed and reachable — give HR a heads-up that a verification call is coming.
- Document every deposit over half your monthly income before it lands.
- Talk to your loan officer before ANY financial move — new account, big purchase, job offer, deposit, dispute. Ten minutes of "hey, is this okay?" costs nothing; a re-underwrite costs your closing date.
The broker advantage: I work with 200+ lenders, and their overlays differ. One lender's "no" on a borderline file is never the last word — the agency guidelines are the agency guidelines, and a broker places your file where it fits. If something already happened mid-process, don't hide it. Bring it to me early.
A Quick Word for Jacksonville Buyers
Around here, the traps have local flavor. PCS moves between NAS Jacksonville and Mayport have families changing jobs and addresses mid-file — if orders shift your employment picture, tell your loan officer the day you find out. Furniture showrooms along Blanding and 103rd run 0%-for-12-months offers aimed at under-contract buyers — Moves #1 and #3 in one signature. And with Florida homeowners insurance doing what it's doing to escrow payments, your housing ratio already carries weight it wouldn't in most states; you have less DTI headroom for a financed living room set. Keep the file boring until the deed records — the couch can wait a week.
Your Turn
Discussion: Were you ever told to "freeze" your financial life during a home purchase — or did a surprise credit move almost cost you a closing? Drop your story in the comments. The best lessons come from the deals that almost died.
Start Here: Know Your Real Number Before You Shop
Thinking about buying — or mid-process and want a second set of eyes? Start with the free quiz; it takes a few minutes and shows you where you stand:
If anything in this post made you nervous about your own file, call me directly.
Douglas Wilkerson
Mortgage Broker, NMLS #1680719
Freeman Douglas Corp
(904) 517-4049
[email protected]
Jacksonville, FL
Freeman Douglas Corporation is a DBA of Edge Home Finance. This is not a promise to lend — all credit decisions are subject to approval. Douglas Wilkerson, NMLS #1680719 | Edge Home Finance, NMLS #891464. Verify licensing at nmlsconsumeraccess.org. Equal Housing Opportunity.
