Dentist Home Loans: How Dentists Buy a Home While Carrying Dental School Debt
By Douglas Wilkerson
Dentists graduate with some of the heaviest student debt of any profession in America. According to the American Dental Education Association (ADEA), indebted members of the dental school Class of 2025 left school owing an average of $297,800 in education debt, and 79% of graduating dental students carried student loans. Then comes the fork in the road almost every new dentist hits: take an associate position, or buy into a practice. Faced with both, most dentists assume the home purchase has to wait years.
In Jacksonville's growing dental market — private practices expanding across the Beaches, Southside, and St. Johns — it usually doesn't have to wait at all. Dentist home loans, built on the same professional loan programs that serve physicians, were designed for exactly this borrower: high income, high education debt, low cash on hand. Here's how they actually work.
Can a Dentist Really Buy a Home With Dental School Debt?
Yes. A dentist carrying $200,000 to $400,000 in student loans can qualify for a home loan today, because professional mortgage programs underwrite the debt differently than a standard conventional loan. The short answer: DDS and DMD holders are eligible for physician-style loan programs that offer low or zero down payment, no private mortgage insurance (PMI), and student-loan treatment based on your actual income-driven repayment (IDR) payment instead of a punitive percentage of your balance.
Lenders offer these programs for a rational reason. The U.S. Bureau of Labor Statistics reports median annual pay of $176,110 for general dentists, with specialists earning considerably more — and dentists have historically low loan default rates. The debt is big, but so is the earning power behind it, and underwriters know it.
How Do Dentist Home Loan Programs Treat DDS and DMD Borrowers?
Professional loan programs (often marketed as "physician loans" or "doctor loans") explicitly include dentists. Eligibility lists at major programs name DDS and DMD alongside MD and DO. The core features, verified against current program guidelines, look like this:
- Low or zero down payment. Representative programs offer 0% down up to $1,000,000 for practicing dentists, 5% down up to $1,500,000, and roughly 10% down up to $2,000,000. Some lenders active in Florida offer 100% financing up to $1,000,000 with total loan amounts up to $2,000,000.
- No PMI at any tier. A conventional borrower putting down less than 20% pays private mortgage insurance. On a $750,000 loan, PMI at roughly 0.5% per year adds about $3,750 annually — over $300 a month — for insurance that protects the lender, not you. Professional programs waive it entirely.
- Student loans counted at the real payment. Under standard conventional guidelines (Fannie Mae B3-6-05), if no payment is documented, an underwriter may have to use 1% of the outstanding balance as your monthly debt — on a $300,000 balance, that's $3,000 a month of phantom debt, which destroys a debt-to-income ratio. Professional programs typically use your documented IDR payment instead, and some exclude loans in deferment or forbearance from the ratio altogether, per program guidelines.
- Primary residence, purchase or rate-and-term refinance. These are home loans, not business loans — cash-out is generally restricted, and the property must be your primary residence.
The caps, credit score minimums (some programs start at 680; others require 720–740), and down-payment tiers differ from lender to lender. That variance is the whole point of working with a broker — more on that below.
Associate Dentist or Practice Owner — Does It Change Your Home Loan?
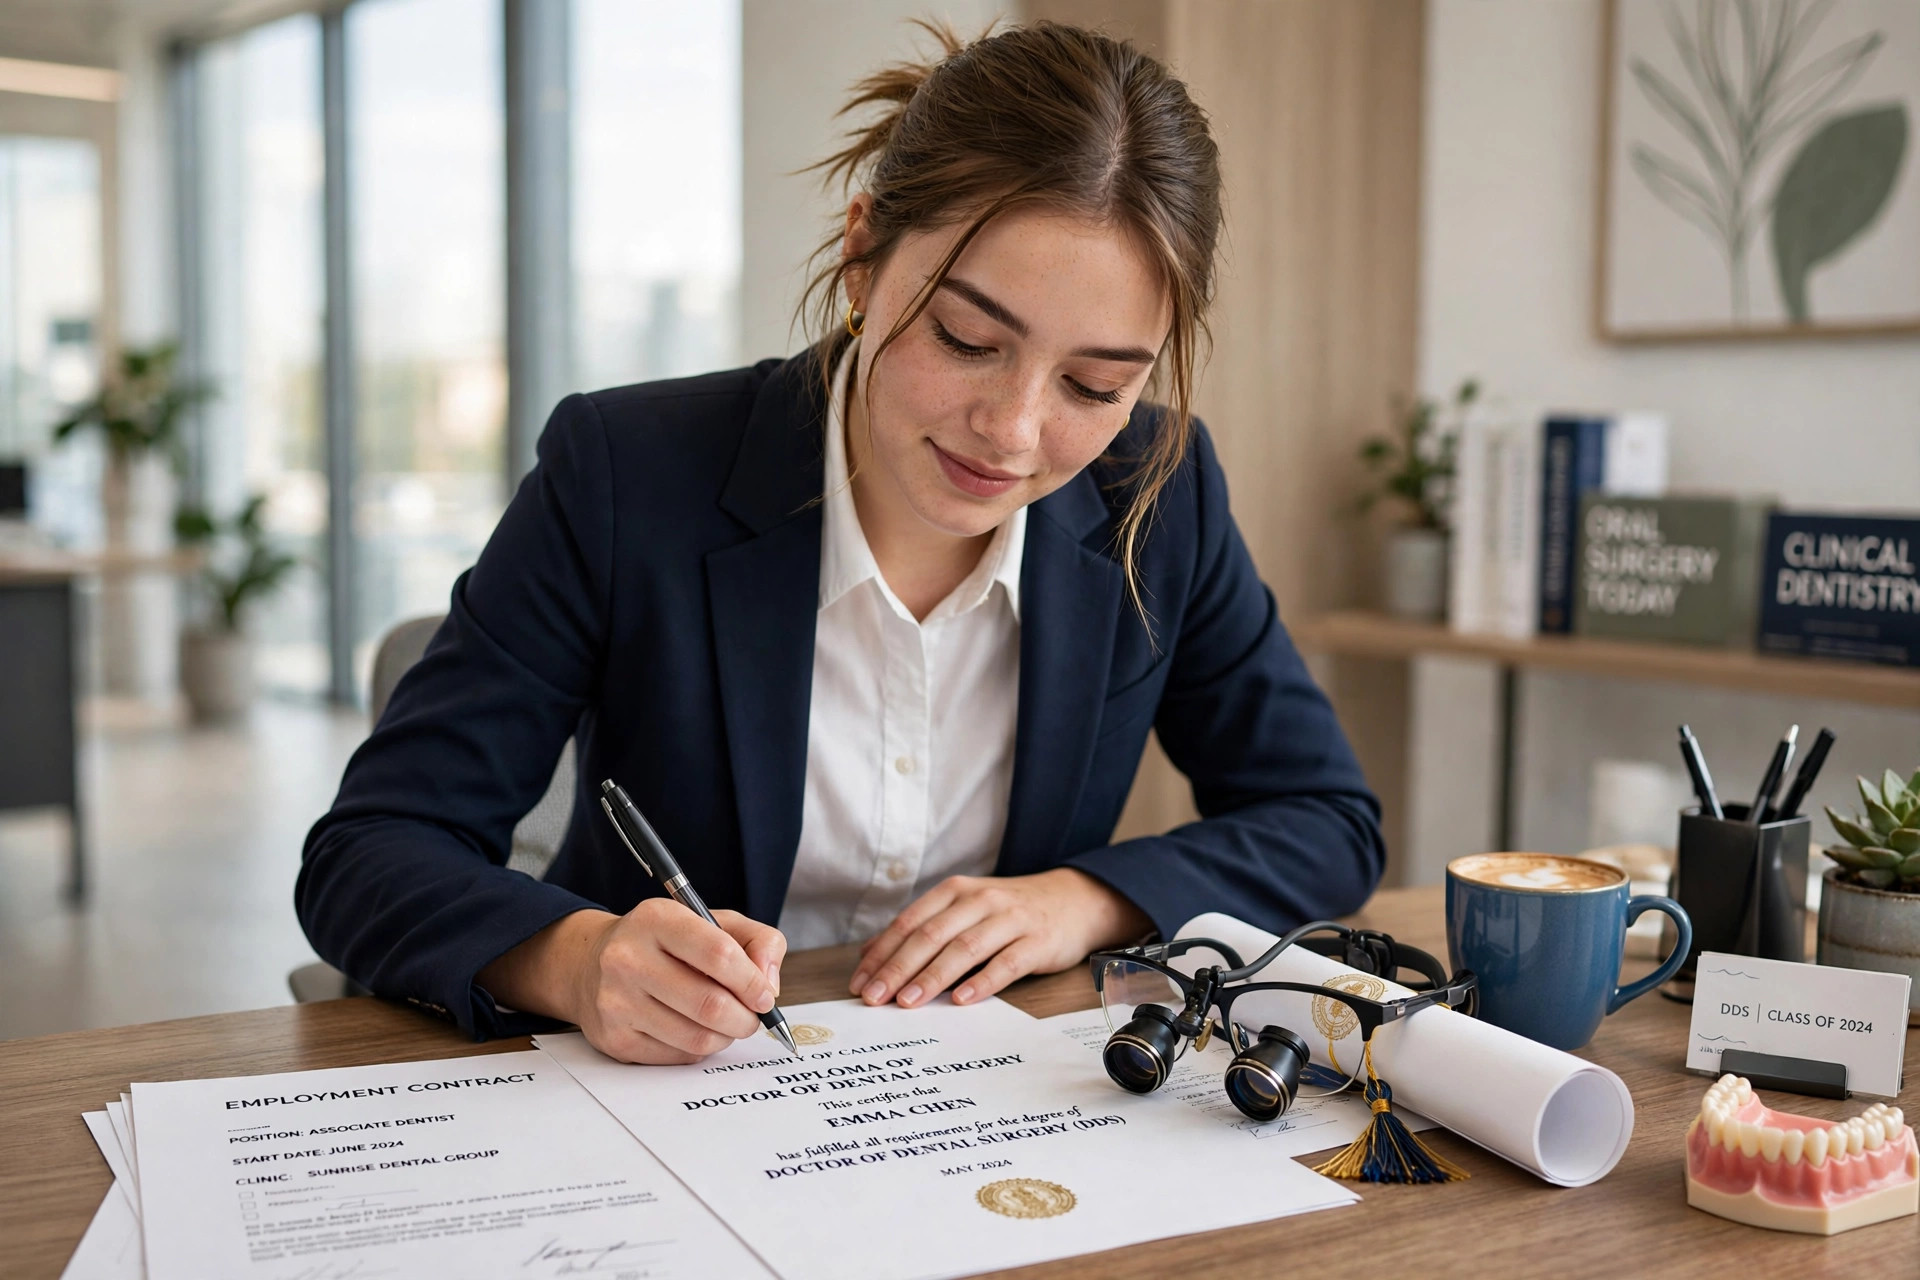
Yes — your employment structure changes your documentation, but both paths lead to a home loan. They just take different paper trails.
The W-2 associate. If you're an associate at a group practice or DSO, you're an employee. Underwriting is the simplest version: a signed employment contract, a verification of employment, and pay stubs once you start. Your income is what the contract says it is.
The practice owner. If you own 25% or more of a practice, Fannie Mae guidelines (B3-3.2-01) treat you as self-employed — even if the practice pays you a W-2. That means the lender analyzes roughly two years of personal and business tax returns, averages your income across that period, and evaluates the financial strength and stability of the business itself. Two details catch dentist-owners off guard:
- Your tax returns write your income. Aggressive deductions lower your tax bill — and lower your qualifying income by the same stroke. The number your CPA engineered is the number the underwriter uses.
- Practice debt can follow you home. A practice acquisition loan or equipment loan that you personally guaranteed may be counted against your personal debt-to-income ratio unless the business demonstrably carries the payment on its own. The underwriter separates what the practice owes from what you owe — and the line between them matters.
None of this blocks a home purchase. It means an owner's file needs more lead time and cleaner documentation than an associate's — and it means the home loan conversation should happen before you structure the practice purchase, not after. (This article covers the home loan only; practice acquisition financing is a separate conversation.)
Can You Buy Before Your Start Date, Using a Signed Contract?
Often, yes. Under standard agency guidelines (Fannie Mae B3-3.3-03), a borrower can qualify on future employment income when a non-contingent signed contract documents the salary and the job starts within 90 days of the loan's note date. Professional dentist programs frequently go further — some allow start dates up to 150 days after closing — because they were built for relocating doctors and dentists whose contracts are signed months before the move.
What the lender documents is straightforward: the executed contract or offer letter showing position, salary, and start date; confirmation the terms aren't contingent on anything outstanding; and reserves to bridge the gap between closing and your first paycheck. For a dentist relocating to Jacksonville for an associate role, that means closing on the house can happen on the same trip as the move — not two rental cycles later.
What Are the Honest Trade-Offs of a Dentist Home Loan?
Professional programs are not magic, and any loan officer who presents them as free money is skipping the fine print:
- Pricing reflects the risk structure. A 0%-down loan with no PMI is priced differently than a 20%-down conventional loan. Sometimes the professional program wins on total monthly cost because the PMI savings swamp the rate difference. Sometimes, if you genuinely have 20% to put down, conventional pricing wins. The only honest answer comes from pricing both structures on the same day.
- Caps and terms vary by lender — a lot. One bank's dentist program caps 0% down at $650,000 for dentists in training; another goes to $1,000,000 for practicing dentists. Credit minimums range from the high 600s to 740. Student-loan treatment differs program by program.
- One bank's terms are never the last word. I broker through roughly 200 lenders. When a single bank's program doesn't fit — wrong cap, wrong start-date window, wrong student-loan treatment — the file goes to the next program, not into a drawer.
I won't quote you a rate in a blog post, because rates move daily and depend on the full file. If anyone shows you a "dentist loan rate," make them attach the date and the term — and the originator's license number. Mine is below, on everything I publish.
What Should a Dentist Do First — Buy the Home or Buy the Practice?
Sequence matters more than speed. A few ground rules from how these files actually underwrite:
- Bring the whole debt picture early. Student loans, a signed contract, a possible practice buy-in — an underwriter who sees all of it on day one can sequence the transactions. One who discovers a personally guaranteed practice loan mid-file cannot.
- If you're an associate with a signed contract, the home can usually come first — your income documents cleanly, and buying the practice later starts from a stable home base.
- If you're buying into a practice soon, plan the two debts together. The practice loan's guarantee can affect your home loan ratio, and the home loan's new payment can affect the practice loan. Done in the wrong order, each one makes the other harder.
- Get priced across programs. Dentist programs differ enough that a single quote is not a market. Apply — an application is how real pricing gets attached to your real file, under actual program guidelines instead of one bank's overlay.
Not sure where your file stands? Take the free VA-Ready Score–style checkup we built for borrowers — or reach out and I'll run your numbers directly.
Start with the free quiz — check your homebuying readiness in minutes
If you could see your real qualifying number — priced across several dentist programs, with your student loans counted at your actual payment — would you still wait, or would you buy this year?
Start Here
I'm Douglas Wilkerson, a mortgage broker in Jacksonville Beach. If you're a dentist — associate, future owner, or relocating to Northeast Florida — send me your contract and your debt picture and I'll tell you plainly what you qualify for and which program structure fits. No pressure, and no bank overlay dressed up as a rule. Call or text me at (904) 517-4049.
Douglas Wilkerson — NMLS #1680719
Direct: (904) 517-4049 | Office: (904) 906-8869
[email protected] | [email protected]
1548 the Greens Way, Ste. 4, Jacksonville Beach, FL 32250
Freeman Douglas Corporation is a DBA of Edge Home Finance. This is not a promise to lend — all credit decisions are subject to approval. Douglas Wilkerson, NMLS #1680719 | Edge Home Finance, NMLS #891464. Verify licensing at nmlsconsumeraccess.org. Equal Housing Opportunity.
