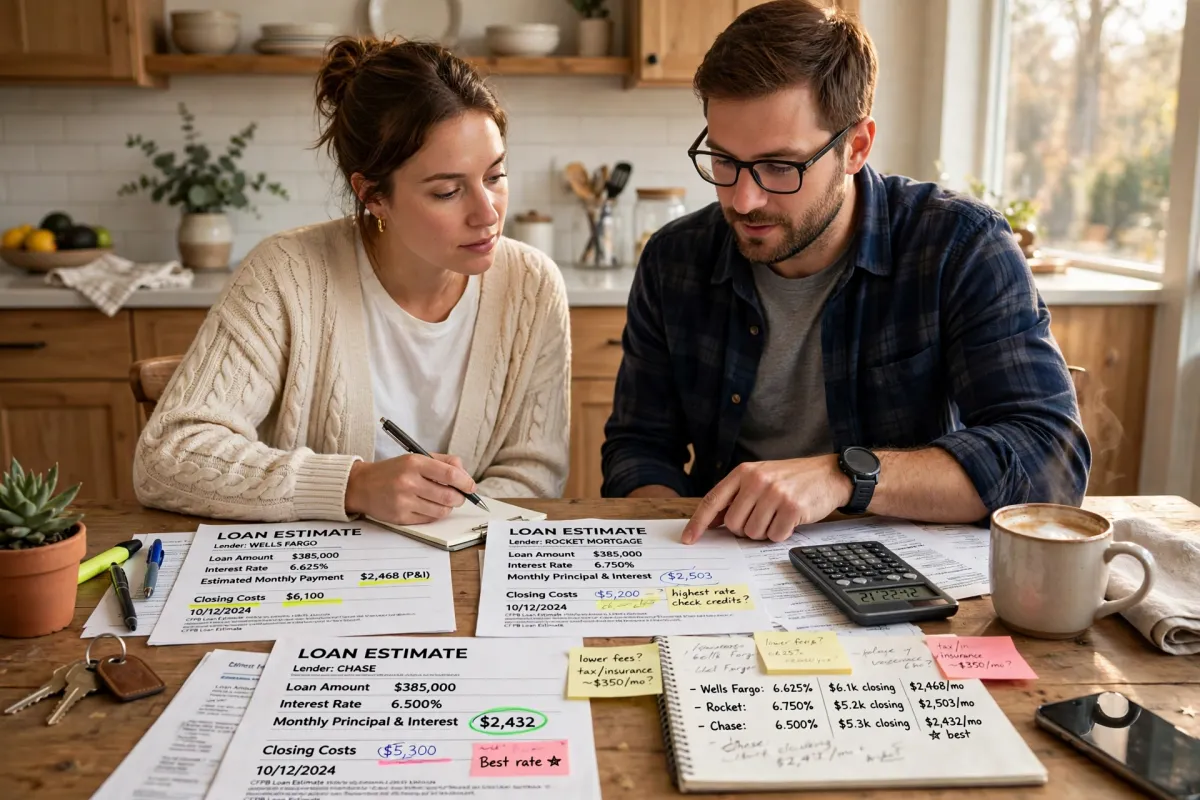
Shopping for a Mortgage Won't Wreck Your Credit Score: The 14-Day and 45-Day Windows, Explained
Shopping for a Mortgage Won't Wreck Your Credit Score: The 14-Day and 45-Day Windows, Explained
Short answer: If you shop for a mortgage the way scoring models expect you to — several lenders, one focused window — the model counts those pulls as a single inquiry, not one hit per lender. FICO ignores mortgage inquiries made in the 30 days before a score is calculated, and for older inquiries it collapses pulls inside a shopping period into one event: 14 days under older FICO versions, 45 days under newer ones. Since you usually do not know which version a lender will use, the safest play is to compress your shopping into 14 days. The fear that comparing five lenders costs you five credit hits is the single most expensive myth in homebuying, because it stops people from finding a better rate.
Hard pull, soft pull, and why only one of them matters here
Most of the panic comes from mixing up two different things. A soft inquiry happens when you check your own credit, when a lender pre-screens you, or when a broker runs a preliminary review without a full application. Soft inquiries do not affect your score at all. Check your own credit as often as you like.
A hard inquiry happens when you formally apply and the lender pulls your full report to decide. That pull is recorded, and it can affect your score. It stays visible on your report for two years, though FICO only factors inquiries from the past 12 months into your score, and the effect fades over those months.
How much does one hard inquiry actually cost? New credit is about 10% of a FICO score, the smallest scoring category, and a single inquiry's typical impact is fewer than five points. When rate-shopping protection applies, that small impact is the total impact, no matter how many mortgage lenders pulled your credit inside the window.
The rate-shopping rule, in plain English
For loans that commonly involve rate shopping — mortgage, auto, and student loans — FICO treats the process in two layers.
Layer one: the 30-day ignore. FICO scores ignore inquiries made in the 30 days prior to scoring. If you find your loan within 30 days, the inquiries do not affect your scores while you are rate shopping.
Layer two: the shopping window. For inquiries older than 30 days, FICO counts the ones inside a typical shopping period as just one inquiry. That period is 14 days under older versions of the formula and 45 days under the newest versions. The Consumer Financial Protection Bureau describes the same 45-day window, and is clear that the score impact is the same whether you consult one lender or ten, as long as the last credit check falls within 45 days of the first.
VantageScore, the other major scoring model, uses a 14-day rolling window for the same purpose: multiple inquiries for the same loan type within two weeks are treated as a single event. The models disagree on the exact number of days. They agree on the principle — which is why the 14-day plan below is the safe one.
| Scoring model | Shopping window | What it means for you |
|---|---|---|
| FICO, older versions | 14 days | Pulls inside any 14-day stretch count as one inquiry |
| FICO, newest versions | 45 days | Pulls inside a 45-day stretch count as one inquiry |
| VantageScore | 14 days, rolling | Same loan type, inside two weeks, counts as one event |
| FICO, all versions | 30 days before scoring | Inquiries in the 30 days before a score is calculated are ignored |
The protection only groups inquiries for the same type of loan. A mortgage inquiry and a credit card application are not grouped together. The model protects comparison shopping, not a general borrowing spree — which is why the plan below keeps everything else frozen while you shop.
What shows on your report is not what your score counts
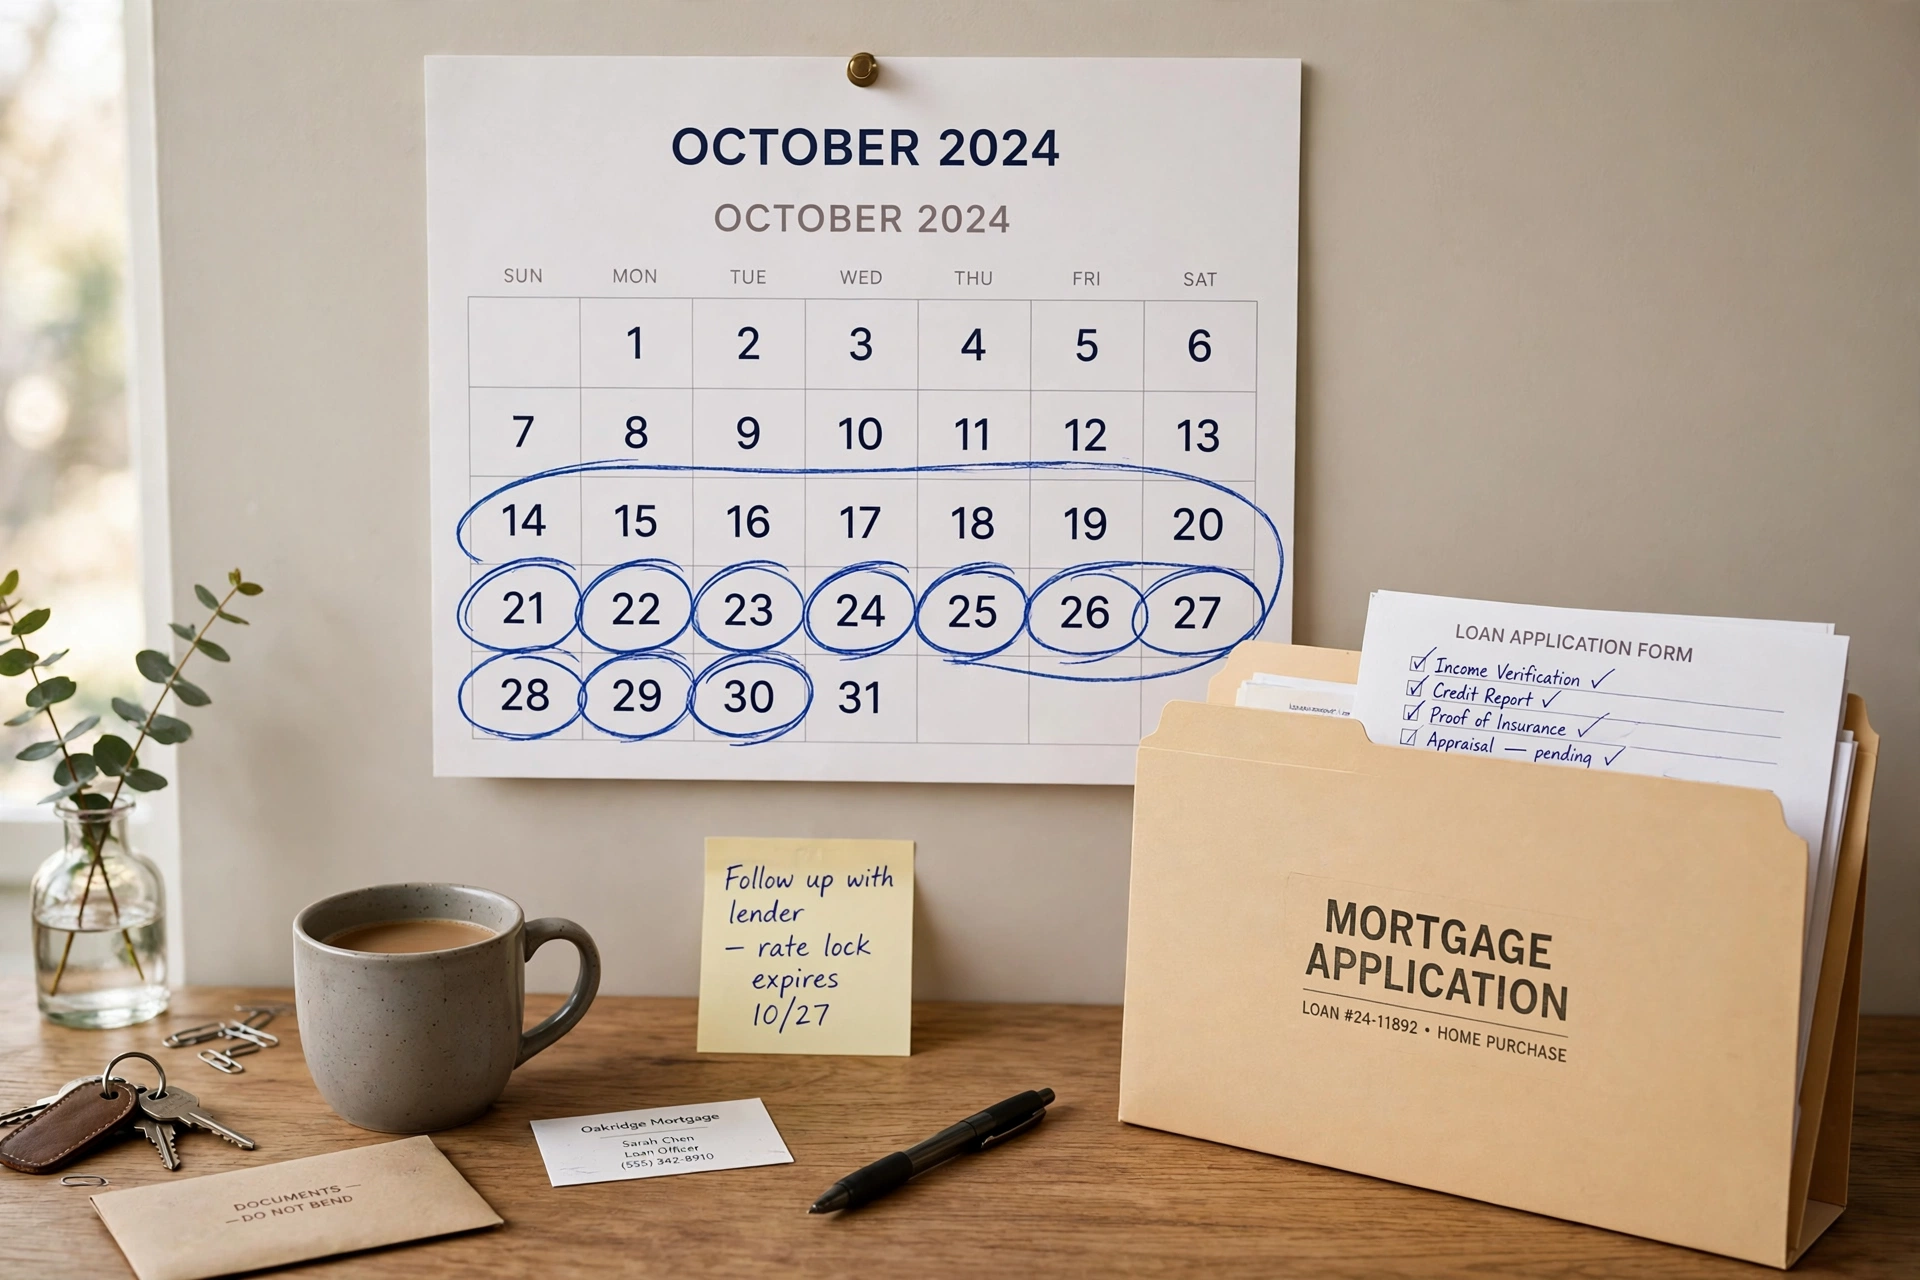
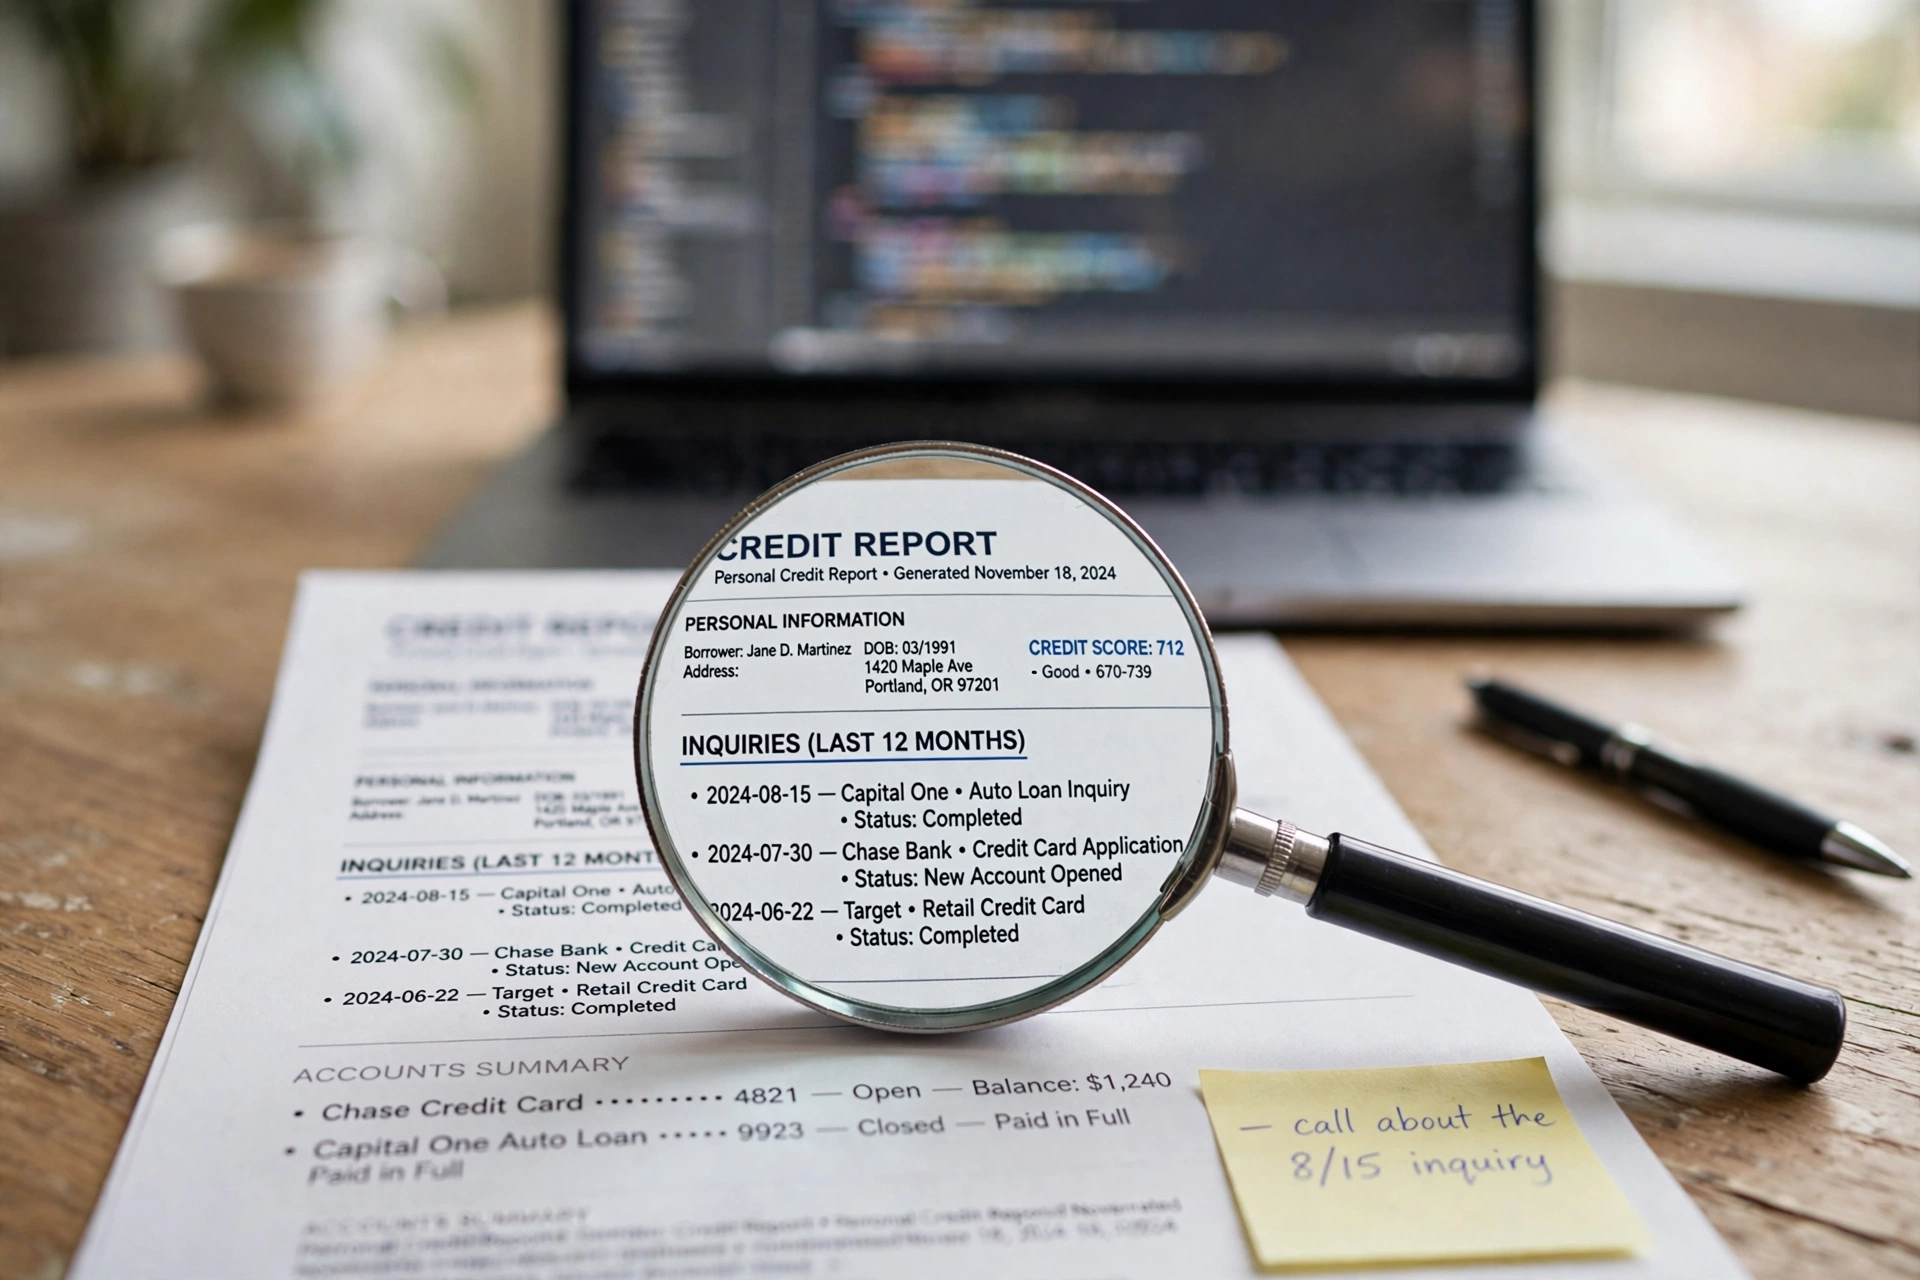
Every lender that pulls your credit appears as a separate line item on your report. If seven lenders pull your credit, your report lists seven names. That is a transparency rule, not a scoring rule. The scoring algorithm groups those entries internally for rate shopping, while the report keeps the full list so you can see who accessed your file.
A future lender can see that you talked to several lenders. That is normal, answered with one sentence: "I was rate shopping for a mortgage." Inside the window, seven pulls on your report did not mean seven hits to your score. Check the dates, not the count.
The 14-day shopping plan
Days 1–2: Get your own house in order, with soft pulls only. Pull your own credit report first — a soft inquiry, no score impact. Gather pay stubs, W-2s, tax returns, and bank statements once, so every lender gets the same file.
Days 3–4: Talk to lenders without authorizing hard pulls yet. Ask each lender to quote on the same assumptions — same loan amount, down payment, lock period, and points — so the quotes are comparable. Ask directly: is this quote based on a soft pull or a hard pull?
Days 5–14: Authorize the hard pulls, all of them, inside the window. Once you have narrowed the field, authorize the real applications in a tight cluster. Do not authorize one this week, one next month, and one after that — that is how a protected shopping trip becomes three separate inquiries.
While you shop: freeze everything else. Do not open a new credit card, finance furniture, or let a car dealer run your credit "just to see." Those are different loan types, not grouped with your mortgage shopping.
After you pick a lender: stop shopping. Once you have a locked rate with a lender you trust, additional mortgage pulls do not help you and only add noise to the file.
Why this is worth doing: the dollar math
Freddie Mac's Primary Mortgage Market Survey for the week ended October 22, 2026 put the 30-year fixed-rate average at 7.32%, down from 7.40% the week before, with the 15-year fixed at 6.68%, down from 6.71%. A year earlier, the 30-year averaged 6.19% and the 15-year 5.44%. Those are national averages for excellent credit, 20% down, conventional conforming — not a quote for you. That is precisely why you shop: the average is not your offer.
On a $350,000 loan, principal and interest only, 30-year fixed:
| Rate | Monthly principal and interest |
|---|---|
| 7.07% | $2,345.04 |
| 7.32% (week ended October 22, 2026 average) | $2,404.26 |
| 7.57% | $2,464.05 |
A quarter point is about $60 a month — about $720 a year. A lender who beats the pack by a quarter point has just paid you far more than any single inquiry could cost you in score terms. The only way to know which lender you are dealing with is to compare real, written Loan Estimates side by side.
The actual guidelines, not one bank's overlay
Many lenders add their own extra rules on top of the agency guidelines — overlays. One lender's overlay says your file needs a higher score or a lower debt ratio than Fannie Mae, Freddie Mac, the VA, or FHA actually require. That lender is not quoting you the guideline. That lender is quoting you its own caution.
The agency guidelines are more forgiving than bank marketing suggests, and a lender that turns you down has given you one lender's answer — not the answer. I broker through 200 lenders, including conventional, FHA, VA, USDA, and private money, hard money, QM, and non-QM programs. When one lender's overlay says no, another lender's actual guideline often says yes, or says yes at a better price. That is the structural reason a broker exists: one application, compared across lenders, instead of one lender's take-it-or-leave-it quote.
Do not let a single lender's credit conversation end your shopping. If a lender says your score is too low, ask which guideline they are citing — agency guideline or house overlay — and get a second read against the real rules.
Three traps that break the protection
Shopping in slow motion. A pull in October, a pull in December, and a pull in February are three shopping events, not one. If life interrupts your shopping, restart the clock consciously when you resume, and re-shop inside a fresh 14-day cluster rather than assuming the old pulls still cover you.
Mixing loan types. A mortgage pull, an auto pull, and a credit card pull in the same week are not one event. The grouping is by loan type. Keep the mortgage window clean.
Pulling credit before you are ready to compare. A hard pull on day one, followed by three weeks of indecision, followed by pulls from the lenders you actually want, can split your shopping across two windows. Have the soft-pull conversations first. Authorize hard pulls when you are ready to decide, not when you are still browsing.
One more trap: assuming a pre-qualification is a pre-approval, or either is a rate lock. Neither locks your rate. Compare locked terms and Loan Estimates, not verbal quotes.
The Jacksonville angle
Jacksonville buyers feel this fear more than most: a first home, a PCS move to Naval Station Mayport or Naval Air Station Jacksonville, or a family upsizing on a timeline they did not choose. None of them can afford to take the first lender's quote as gospel.
At the October 22 average of 7.32% for a 30-year fixed loan, a $300,000 loan carries $2,060.79 a month in principal and interest — versus $1,835.46 a year earlier at 6.19%. For veterans: the VA benefit does not change the inquiry rules, but VA loans have no down payment requirement and no monthly mortgage insurance in the conventional sense, so the rate and lender fees carry even more of the total cost. Shopping your VA loan across lenders — inside the same 14-day window — is how you protect the benefit you earned.
What to do this week
If you have been putting off shopping because of your credit score, here is your assignment. First, pull your own credit — soft inquiry, no harm. Second, pick a 14-day window on your calendar and tell the lenders you talk to that you are shopping inside it. Third, get written Loan Estimates on identical assumptions from at least three lenders, or from a broker who can show you several lenders' terms side by side. Fourth, compare rate, points, lender fees, and lock period — not just the rate headline. Fifth, lock in writing.
If a lender tries to scare you out of step three, you now know the answer: FICO ignores mortgage inquiries from the 30 days before scoring and groups the rest inside a 14- or 45-day window as a single inquiry. You are not being reckless by shopping. You are being reckless by not shopping.
So here is the question I want to hear from you: did a lender ever talk you out of comparing offers by warning you about your credit score — and what did that one lender's quote end up costing you? Tell me in the comments. I read every one.
Start Here
If you are ready to shop properly — several lenders, one window, real numbers — start with the 60-second quiz below.
Check Your Rate — 60-Second Quiz
Related reading: Your Statement Date Matters More Than Your Due Date: The Credit Utilization Playbook for Mortgage Shoppers — the other half of the credit-score playbook, and the date that moves your score more than any inquiry will.
Douglas Wilkerson — NMLS #1680719
Direct: (904) 517-4049 | Office: (904) 906-8869
[email protected] | [email protected]
1548 the Greens Way, Ste. 4, Jacksonville Beach, FL 32250
Freeman Douglas Corporation is a DBA of Edge Home Finance. This is not a promise to lend — all credit decisions are subject to approval. Douglas Wilkerson, NMLS #1680719 | Edge Home Finance, NMLS #891464. Verify licensing at nmlsconsumeraccess.org. Equal Housing Opportunity.
