PCS to NAS Jacksonville or Mayport: Should You Buy Before You Arrive?
PCS to NAS Jacksonville or Mayport: Should You Buy Before You Arrive?
By Douglas Wilkerson, Mortgage Broker, NMLS #1680719 | November 15, 2026
The Short Answer
Yes — with PCS orders in hand, you can buy a home in Jacksonville before you ever set foot in it, and a VA loan is built for exactly this move. The VA's occupancy rule is satisfied by your spouse moving in, or by your own certified move-in date tied to your report date. Your lender qualifies you on the BAH for your gaining station, not the one you're leaving, and the tax-free allowance gets grossed up 25% for qualifying. On a $300,000 Jacksonville home at today's rates, an E-5's $2,181 monthly BAH covers the entire principal-and-interest payment, with about $411 a month of taxes and insurance coming out of base pay. The question is not whether the VA allows it. The question is whether your timeline, your lock, and your inspection are lined up before you sign.
What "Buy Before You Arrive" Actually Looks Like
Every PCS move to NAS Jacksonville or Naval Station Mayport follows the same rough calendar, and the families who buy smoothly are the ones who start the money part before they start the house-hunting part. Here is the order that works:
Orders drop. You cannot schedule a move — or get a lender to underwrite your gaining-station BAH — until official orders exist. Military OneSource is blunt about this: no move is scheduled until orders are in hand. For most CONUS moves, orders land three to six months before your report date. That window is your buying window.
Get preapproved on the Jacksonville numbers. The moment orders exist, a preapproval can be run on your new BAH and your new pay. A preapproval tells you your real price ceiling in Jacksonville before you fall in love with a house above it.
Take the house-hunting trip. The military gives you up to 10 days of house-hunting leave — permissive TDY/TAD, not charged against your leave balance — to look at housing at your new duty station. Two honest details: it is self-funded (you pay your own travel and lodging), and 10 days sounds generous until you subtract travel days, weekends, and the reality that a lender needs two to three weeks from accepted offer to clear title and fund. Treat the trip as a closing trip with showings built in, not a sightseeing week. If your spouse can travel separately, even better — a spouse-led trip needs no separate approval, and your spouse is the one who can satisfy the VA occupancy rule while you are still at your old station.
Offer, inspect, close — before you report. A normal VA purchase closes in 30 to 45 days from an accepted offer. Work backwards from your report date: offer accepted 45 days out, close 30 days out, spouse moves in, you report on time and move into a home you already own.
Can You Use a VA Loan If You Haven't Moved Yet?
This is the question that stops most PCS buyers before they start, and the answer is written into federal law — not lender policy. Under 38 U.S.C. 3704(c), a VA purchase loan cannot be guaranteed unless you certify that you intend to occupy the property as your home. The VA Lenders Handbook (Pamphlet 26-7, Chapter 3, Topic 5) fills in what "intend" means, and it was written by people who understand military life:
- Sixty days is the standard. VA defines a "reasonable time" to move in as within 60 days after loan closing. That is the default expectation for your own move-in.
- Your spouse can satisfy it. If you are on active duty and cannot personally occupy the home within a reasonable time, occupancy — or intent to occupy — by your spouse satisfies the requirement. Your spouse checks the active-duty spouse box on VA Form 26-1820, the Report and Certification of Loan Disbursement, and signs it. A dependent child's occupancy can satisfy it as well.
- A later date can still count. If you cannot move in within 60 days, the VA can still treat a later date as reasonable when you certify a specific occupancy date and point to a particular future event that makes occupancy possible on that date. A report date on PCS orders is exactly that kind of event. That is why buying at your next duty station ahead of arrival works inside the rule instead of around it.
- Twelve months is the outer wall. Occupancy more than 12 months after closing generally cannot be considered reasonable by the VA. If your report date is more than a year out, you are too early — wait, and buy closer to the move.
None of this is a loophole, and none of it is a lender doing you a favor. The occupancy rule exists to keep VA loans for primary residences, and a family PCSing to Jacksonville with orders in hand is the definition of a primary residence. What the rule does not allow is buying a house you never intend to live in and calling it a PCS purchase. Intent is the whole test — and orders, a move-in date, and a spouse in the house are the proof.
What BAH Will You Actually Get in Jacksonville?
Both NAS Jacksonville and Naval Station Mayport sit in the same military housing area — Jacksonville, FL, MHA FL058. That means the BAH table is identical at both bases: same rank, same dependency status, same rate, whichever gate you drive through. The 2026 rates, published by the Defense Travel Management Office and effective January 1, 2026, are:
| Pay grade | With dependents | Without dependents |
|---|---|---|
| E-5 | $2,181 | $1,803 |
| E-6 | $2,241 | $1,920 |
| E-7 | $2,283 | $2,049 |
| O-3 | $2,364 | $2,211 |
Three things about this table matter for your budget. First, the with-dependents rate is one rate — it does not grow with the number of dependents. One child and four children draw the same $2,181 for an E-5. Second, 2027 rates are not published yet. The Defense Department typically releases the next year's rates in mid-December — the 2026 rates came out December 11, 2025 — and they take effect January 1, 2027. If your report date is in 2027, budget on the 2026 table. Third, Jacksonville's 2026 rates actually fell slightly from 2025 — an E-5 with dependents went from $2,226 to $2,181, about 2% down — because the Defense Department surveys local rental costs every year and Jacksonville's rents softened. A family PCSing into Jacksonville gets the new, lower table. Budget on the number in the table today, not the number from your last duty station.
How BAH Turns Into Qualifying Income
Here is where a PCS file gets stronger than most buyers realize — and where a lender who does not work with military files can quietly cost you a house.
BAH counts as income. Basic Allowance for Housing is regular, verifiable, tax-free pay, and a VA lender counts it in the debt-to-income calculation. Your Leave and Earnings Statement documents it, and your orders document that the Jacksonville rate applies. Once orders are issued, the lender underwrites the file on the BAH for the duty station on those orders — the gaining station, not the one you're leaving. If you are coming from San Diego's $4,000-plus BAH to Jacksonville's $2,181, the file is priced on Jacksonville, which is exactly right, because Jacksonville is where the mortgage will be paid. The reverse is also true: a family PCSing from a low-BAH station into Jacksonville qualifies on the higher Jacksonville rate.
The 25% gross-up. Because BAH is not taxed, the VA Lenders Handbook (Chapter 4) lets the lender gross it up for the DTI calculation — the standard adjustment is 125% of the verified non-taxable amount. An E-5's $2,181 of BAH counts as $2,726.25 of qualifying income. An E-6's $2,241 counts as $2,801.25. An O-3's $2,364 counts as $2,955.00. That extra $545 a month on an E-5 file is often the difference between a DTI that passes and one that does not. It is not extra cash — your bank account still gets $2,181 — but for qualifying purposes the underwriter treats tax-free dollars as worth more than taxed ones, because they are. If a lender runs your file without the gross-up, ask why. The same treatment applies to BAS and to VA disability compensation.
Residual income is the second test, and PCS files usually pass it easily. The VA does not stop at DTI. It also runs a residual income test — the dollars left after the mortgage, taxes, debts, and living costs — against a table by region and family size. For a family of four in the South region, the line is $1,003 a month (38 CFR 36.4340(e)). A PCS file with BAH, base pay, and BAS stacked together usually clears that line by a wide margin, even when the DTI runs past the VA's 41% guideline. The full table and the 120% automatic-pass rule are in our earlier post on residual income.
The Math on a Real Jacksonville Purchase
Take an E-5 with six years of service, PCSing to NAS Jacksonville with a spouse and two kids. The 2026 numbers, all verified: base pay $4,110 a month (2026 DFAS pay table, after the 3.8% raise effective January 1, 2026), BAH $2,181 with dependents, BAS $476.95 for enlisted members. Monthly cash: $6,767.95. Qualifying income with the BAH grossed up: $4,110 + $2,726.25 + $476.95 = $7,313.20.
Now the house. Jacksonville's median listing price in October 2026 was $294,750, per Realtor.com — so take a $300,000 home, right at the middle of the market. Zero down, first use of VA entitlement. The 2.15% VA funding fee is $6,450, financed into the loan, so the loan amount is $306,450. Principal and interest at 7.11% — the Freddie Mac Primary Mortgage Market Survey 30-year fixed average for the week ended November 12, 2026, a conventional benchmark, not a VA quote — comes to $2,061.51 a month. Add property taxes of $280 a month and homeowners insurance of $250 a month, and the full PITI is $2,591.51.
Here is the number that surprises people: the BAH alone covers the entire principal-and-interest payment. $2,181 of BAH against $2,061.51 of P&I leaves $119.49 to spare. What BAH does not cover is the rest of the payment — $410.51 a month of taxes and insurance comes out of base pay. That is the honest version of "BAH pays the mortgage." It pays the loan. Base pay carries the taxes and insurance. A lender or agent who tells you BAH covers the whole payment is rounding in their favor.
Drop the price to $275,000 and the picture tightens further in your favor: the funding fee is $5,912.50, the loan is $280,912.50, P&I is $1,889.72, and PITI (taxes $257, insurance $229) is $2,375.72 — only $194.72 a month beyond the BAH. And the file itself is comfortable: with $300 a month in other debts, the DTI is ($2,591.51 + $300) ÷ $7,313.20 = 39.5%, under the VA's 41% guideline. Run the residual income test and it is not close: $6,767.95 of cash, minus $2,591.51 PITI, minus $300 in debts, minus roughly $600 in federal tax withholding, minus a $252 maintenance-and-utilities line (1,800 square feet at the VA's 14 cents per square foot) leaves $3,024.44 — more than three times the $1,003 South-region line for a family of four, and far above the $1,203.60 that triggers the VA's automatic pass. With full VA entitlement there is no VA loan limit at all — the 2026 conforming limit of $832,750 is a reference point, not a ceiling — and a $300,000 Jacksonville home is nowhere near it. The constraint is never the program. It is the payment, and the payment works.
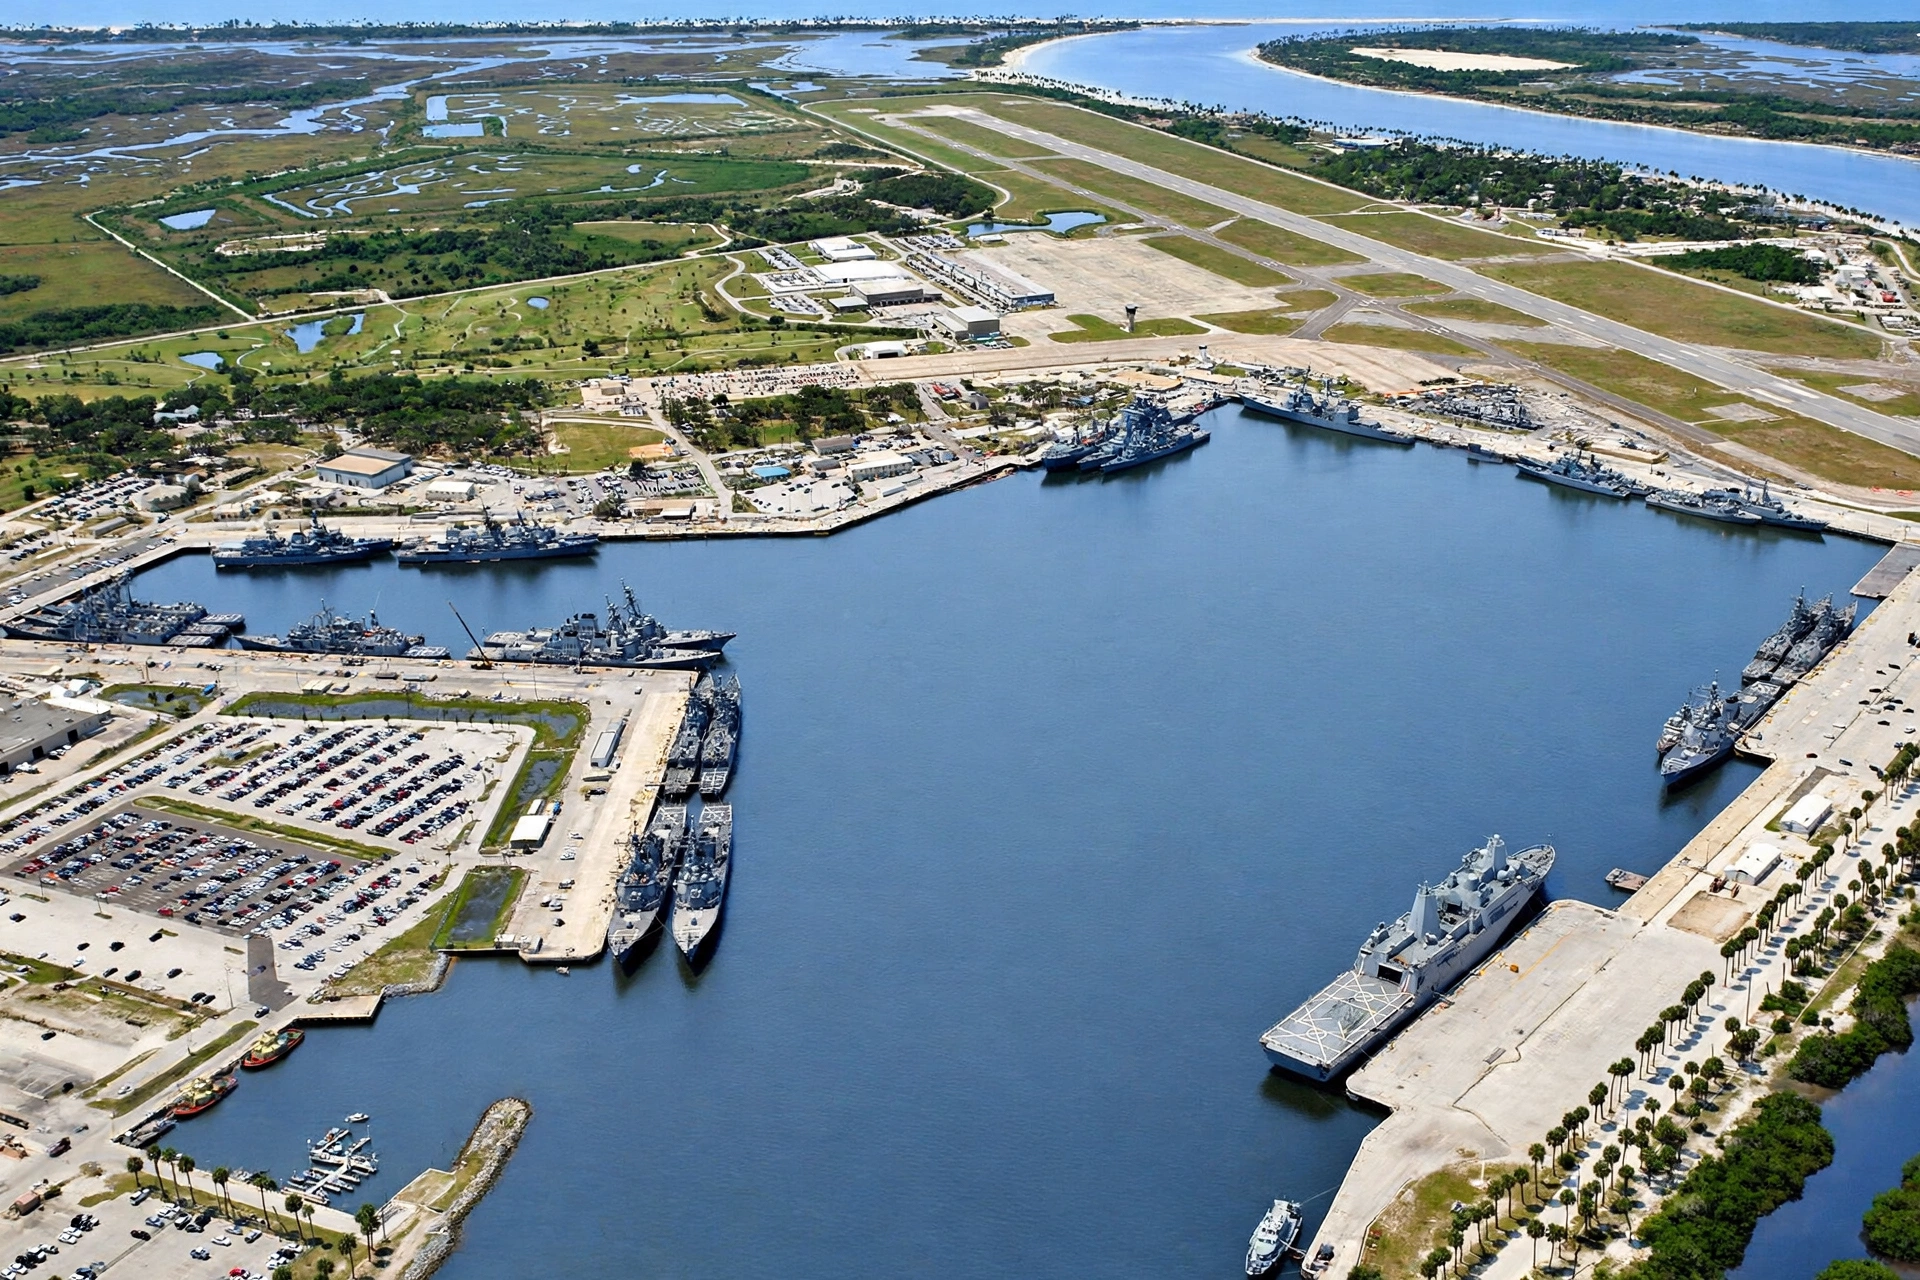
NAS Jacksonville vs. Mayport — Same BAH, Different Map
The allowance is identical, but the two bases sit on opposite sides of the city, and where you buy decides what your mornings look like for the next three years. NAS Jacksonville sits on the westside, on the St. Johns River near Orange Park. The neighborhoods around it — Orange Park, the westside, Fleming Island just south in Clay County — are where most NAS Jax families land: shorter commute, established suburbs, and some of the most affordable square footage in the metro. Naval Station Mayport sits on the Atlantic coast, east of the Intracoastal Waterway. The families there tend toward Atlantic Beach, Jacksonville Beach, and the east side — closer to the ocean, higher prices per square foot, and a commute that crosses the Intracoastal every morning.
Pick the base first and the neighborhood second. A family that buys near Mayport and then gets orders to NAS Jax — or the reverse — has a cross-town commute for the rest of the tour. And if there is any chance of a follow-on tour at the other base, buy in the middle: the Southside and Mandarin put both gates within a reasonable drive, and both hold resale value because the military demand never leaves the market. Jacksonville is a Navy town. The next family PCSing in is your future buyer.
The Traps That Catch PCS Buyers
Buying before you arrive is a good plan with a few sharp edges. The ones that actually cost families money:
Buying sight unseen without an inspection. A video walkthrough is not an inspection. In a Florida market, the inspection is where the roof age, the AC, the water heater, and the flood-zone reality show up — and a VA appraisal will flag minimum property requirements on top of that. If you cannot be there, send someone you trust, or hire an inspector and read every page. A house that looks fine on a phone screen can carry a $12,000 roof the VA appraiser will not let you ignore.
Assuming BAH covers the whole payment. As the math above shows, BAH covers the principal and interest on a $300,000 home and leaves taxes and insurance to base pay. A family that budgets "BAH equals mortgage" and forgets the $530 a month of taxes and insurance is budgeting $6,360 a year short.
Lock timing. A rate lock typically runs 30 to 60 days. Close too early and you are paying a mortgage on an empty house while you are still at your old station. Close too late and the lock expires before funding — or your report date arrives before you have keys. The sweet spot is closing 2 to 4 weeks before you report: the house is yours, your spouse is moved in, and you arrive to a home, not a hotel.
Orders change. Orders can be modified, delayed, or cancelled. It is rare, but it happens — and a closed purchase is not something you unwind. If your orders carry any uncertainty, talk to your command before you go under contract, not after. And never waive an appraisal or inspection contingency to win a bidding war on a house you have not stood inside.
Getting preapproved on the wrong BAH. A lender who runs your file on your current station's BAH instead of Jacksonville's is pricing the wrong house. The preapproval should say Jacksonville, MHA FL058, on the numbers above. If it does not, the preapproval is not yours.
Renting first is not failure. If your report date is sooner than your buying timeline allows, renting for a tour is a reasonable choice. But renting costs you the move twice — once into the rental, once into the house — and every month of rent is a month of equity you did not build. If the orders, the preapproval, and the inspection line up, buying before you arrive is the move that pays you back for the whole tour.
Sources
- Defense Travel Management Office (DTMO), 2026 BAH rate tables, effective January 1, 2026: Jacksonville, FL military housing area FL058 — E-5 with dependents $2,181, E-6 $2,241, E-7 $2,283, O-3 $2,364; E-5 without dependents $1,803. NAS Jacksonville and Naval Station Mayport share MHA FL058. 2027 rates not yet published as of November 15, 2026; DoD typically releases next-year rates in mid-December.
- 38 U.S.C. 3704(c) and VA Lenders Handbook, Pamphlet 26-7, Chapter 3, Topic 5 (Occupancy): reasonable time means within 60 days after loan closing; spouse or dependent-child occupancy satisfies the requirement for an active-duty veteran who cannot personally occupy in a reasonable time; a later specific occupancy date tied to a particular future event (such as a report date) may be reasonable; occupancy beyond 12 months after closing generally cannot be considered reasonable. Occupancy certification on VA Form 26-1820.
- VA Lenders Handbook, Pamphlet 26-7, Chapter 4: non-taxable income (including BAH) may be grossed up to 125% of the verified amount for debt-to-income purposes; residual income tables at 38 CFR 36.4340(e) (South region, family of four, loans $80,000 and above: $1,003 a month; 120% automatic-pass rule at 36.4340(c)(3)); maintenance and utilities at 14 cents per square foot.
- DFAS 2026 military pay tables, effective January 1, 2026: E-5 with over 6 years of service, $4,110.00 a month in basic pay (3.8% raise); enlisted Basic Allowance for Subsistence $476.95 a month.
- Freddie Mac Primary Mortgage Market Survey, released November 12, 2026: 30-year fixed 7.11%, 15-year fixed 6.45% (week ended November 12, 2026; a year ago 6.24% and 5.49%). Conventional conforming benchmark for borrowers with 20% down and excellent credit — not a VA rate quote.
- Realtor.com Economic Research, October 2026: Jacksonville median listing price $294,750.
- VA.gov — VA funding fee rates, effective April 7, 2023 and still current: 2.15% first use with zero down, 3.30% subsequent use under 5% down.
- Federal Housing Finance Agency: 2026 conforming loan limit $832,750.
- House-hunting leave: up to 10 days of permissive TDY/TAD for residence hunting, not charged against leave, self-funded (no travel pay or per diem), per service regulations (Army Regulation 600-8-10; Navy MILPERSMAN 1810-280). Military OneSource: no PCS move is scheduled until official orders are in hand.
Our Take
The VA loan was written for this exact move — a service member with orders to a new duty station, buying the home their family will live in before they get there. The occupancy rule, the spouse provision, the BAH gross-up, the zero-down structure: none of it is an accident, and none of it is a favor a lender does for you. It is the program working the way Congress wrote it. What turns a good program into a good outcome is the order of operations — orders, then preapproval on Jacksonville numbers, then the house-hunting trip, then a close timed to your report date — and a broker who will run the file on the actual VA guidelines instead of one lender's overlay. With 200 lenders to shop, one lender's "we can't use your gaining-station BAH" or "your DTI is too high" is never the last word. It is the first word of a second opinion.
Here's the question: if you PCSed to Jacksonville, did you buy before you arrived — or rent first and wish you hadn't? What would you tell the family getting orders right now? Tell us in the comments.
Your Next Step
Check Your Rate — Free — see what rate you actually qualify for across 200+ lenders. Free, no credit check, no pressure.
PCS orders to NAS Jacksonville or Mayport in hand? Start with the PCS to NAS Jacksonville guide — then run your real numbers on the VA Buy Power Calculator and bring the result to Douglas to price across 200 lenders.
Prefer to talk it through? Call Douglas direct: (904) 517-4049.
Douglas Wilkerson — NMLS #1680719
Mortgage Broker, Branch Manager
Direct: (904) 517-4049
[email protected] | [email protected]
1548 the Greens Way, Ste. 4, Jacksonville Beach, FL 32250
Freeman Douglas Corporation is a DBA of Edge Home Finance. This is not a promise to lend — all credit decisions are subject to approval. Douglas Wilkerson, NMLS #1680719 | Edge Home Finance, NMLS #891464. Verify licensing at nmlsconsumeraccess.org. Equal Housing Opportunity.
