Physician Loans in Florida: How Doctors Buy a Home With Little or Nothing Down — and No PMI
By Douglas Wilkerson
Here is the assumption I hear from almost every doctor relocating to Jacksonville: "I have six figures of student loan debt, I don't have 20% to put down, and my contract doesn't even start for two months — so we'll rent for a few years and buy later."
That assumption is expensive. Jacksonville is a medical town. Mayo Clinic, Baptist Health, UF Health Jacksonville, Ascension St. Vincent's, and Wolfson Children's Hospital recruit residents, fellows, and attendings here every single year — and every year, physicians pay Jacksonville landlords rent money that could have been building equity, because nobody told them a loan product exists that was built specifically for their balance sheet. It's called a physician loan, and if you're a doctor moving here, it should be the first structure you price — not the last.
What Is a Physician Loan, Exactly?
A physician loan is a portfolio mortgage program designed for medical professionals: it allows little or no down payment on loan amounts well above the conventional conforming limit, charges no private mortgage insurance (PMI) even with nothing down, and underwrites student loan debt and future income differently than a standard loan.
"Portfolio" is the key word. The lender keeps this loan on its own books instead of selling it to Fannie Mae or Freddie Mac. Because the lender isn't bound by agency rules, it can write its own guidelines around how doctors actually earn and owe money. The published terms at major programs show how different those guidelines are:
- Truist's Doctor Loan offers practicing physicians and dentists (MD, DO, DPM, DDS, DMD) 100% financing on loans up to $1,000,000, 95% financing up to $1,500,000, and roughly 90% financing up to $2,000,000 — with no mortgage insurance at any tier. Licensed residents, interns, and fellows in MD, DO, and DPM programs qualify for loans up to $1,000,000.
- Bank of America's Doctor Loan starts at 3% down on mortgages up to $850,000, then 5% down up to $1,000,000, 10% up to $1,500,000, and 15% up to $2,000,000 — also with no PMI requirement.
- Other published programs go further: 0% down up to $1,500,000 exists in the market, with stepped down payments above that.
Compare that to a conventional loan, which caps out at the 2026 baseline conforming limit of $832,750 before it becomes a jumbo — and jumbos traditionally want 10–20% down plus months of reserves. The physician program removes both walls at once.
How Do Physician Loans Treat Your Student Loan Debt?
This is where most physicians get wrongly declined by standard underwriting, so let's do the math. On a conventional loan, when your credit report shows a $0 student loan payment (deferred or in forbearance), Fannie Mae's rules make the lender count 1% of your balance as a monthly payment. On a $300,000 med school balance, that's a $3,000-a-month phantom debt stacked into your debt-to-income ratio — even though you currently pay nothing. Deals die on that one line item.
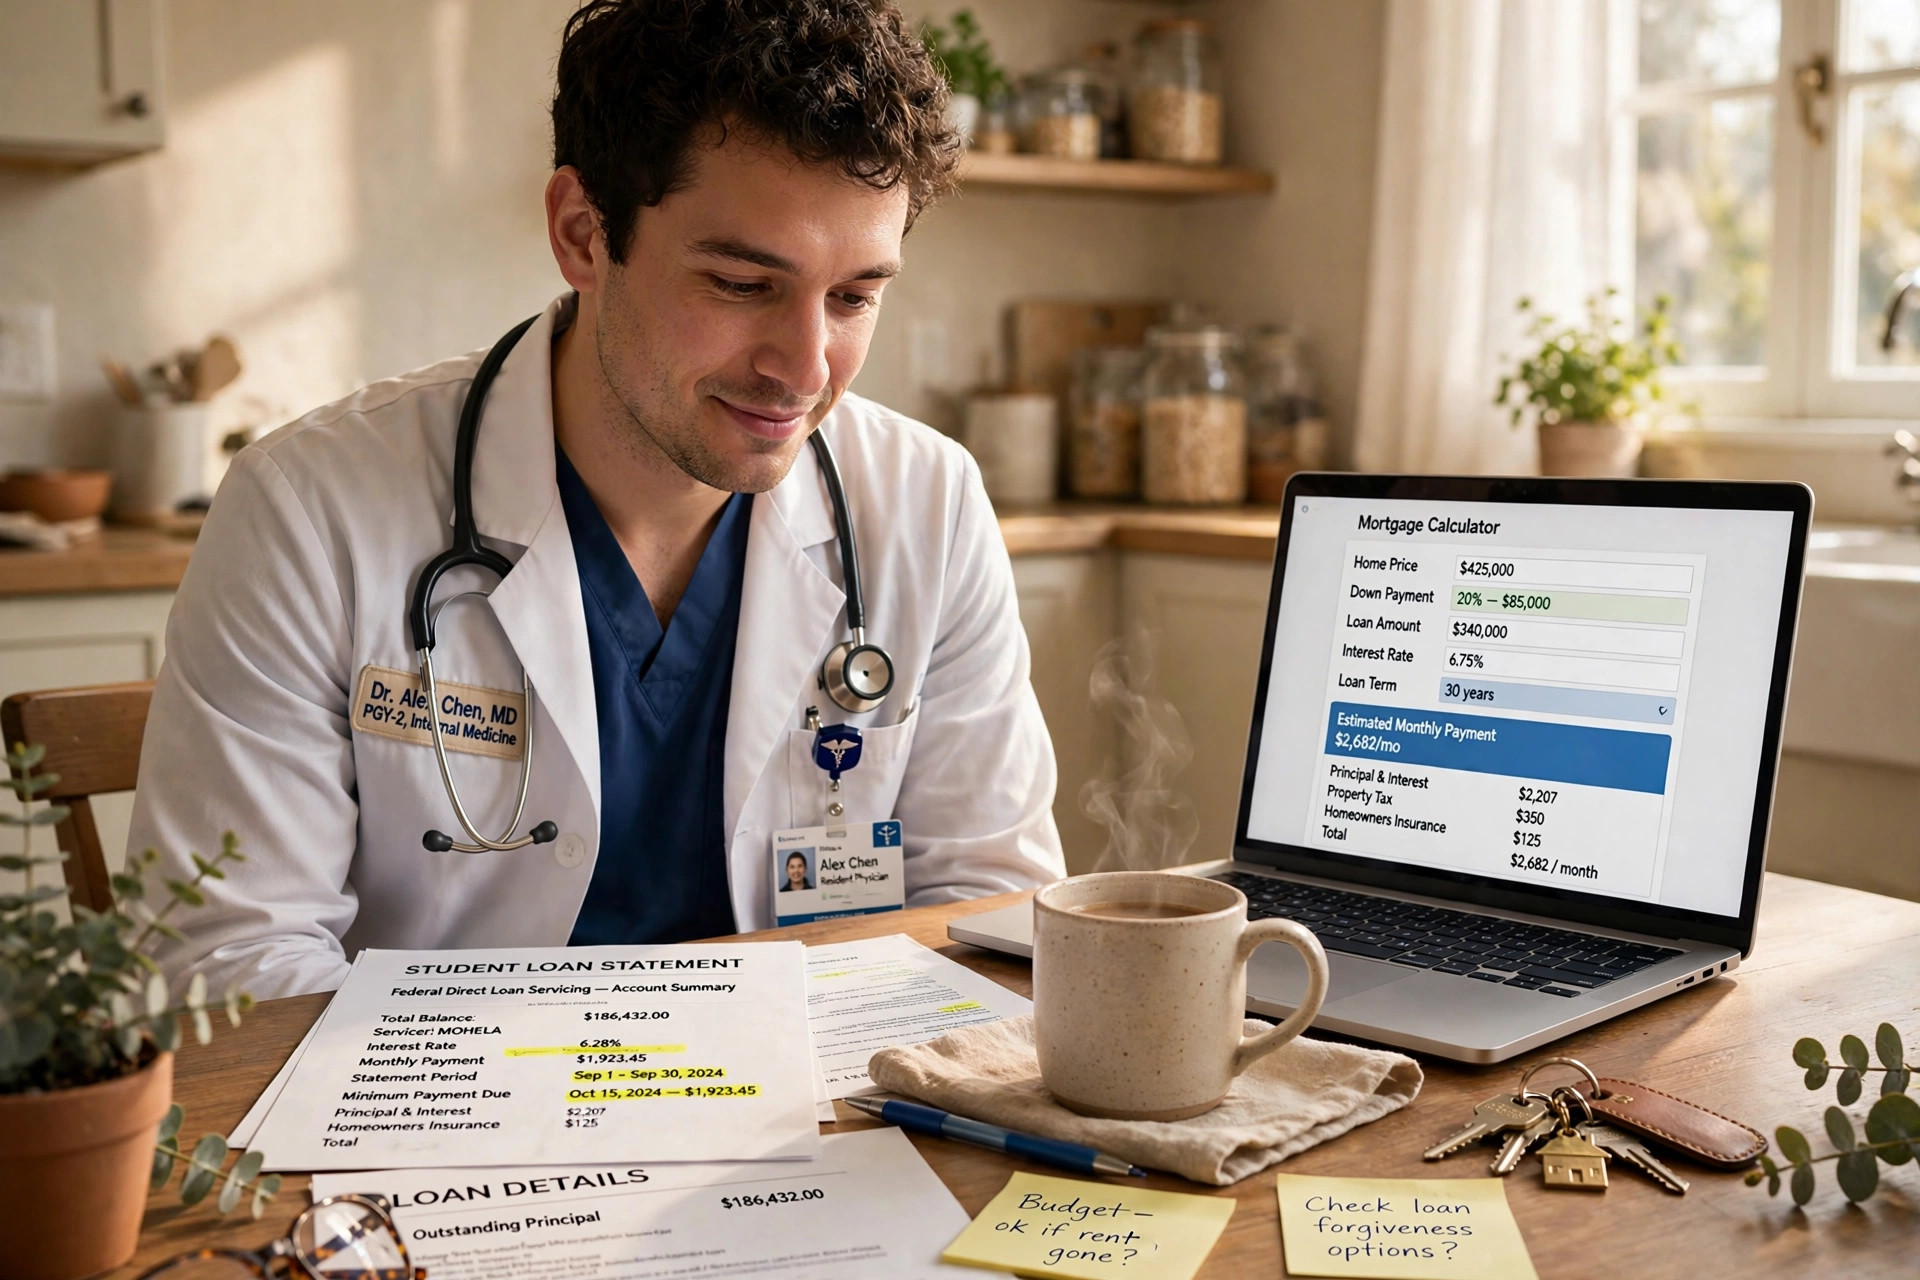
Physician programs attack that problem directly. Truist's published guidelines state that student loan debt may be excluded from the debt-to-income calculation entirely if it will be deferred for at least 12 months after closing, and that reduced payments under an eligible income-driven repayment (IDR) plan may be accepted. Bank of America publishes that student loan debt may be excluded from the total debt calculation under its Doctor Loan. In plain terms: many physician programs use your actual IDR payment — or zero, if your loans are properly deferred — instead of a percentage of your balance. On that same $300,000 balance, the difference between a $3,000 phantom payment and a $350 actual IDR payment is the difference between a denial and an approval.
Can You Actually Close Before Your First Day of Work?
Yes — and this is the mechanism most relocating physicians don't know exists. Standard underwriting wants pay stubs you don't have yet. Physician programs instead underwrite your future income from a signed employment contract or residency/fellowship agreement, so you can close on the Jacksonville home before the job starts and move in once, instead of renting for a lease term and moving twice.
Bank of America publishes that Doctor Loan borrowers can start their new position up to 90 days after closing. Some programs will work with contracts further out than that. The documentation is straightforward: your fully executed employment contract or offer letter showing position, compensation, and start date; your medical license or proof of residency/fellowship placement (Match letter); and verification that the employer is real and the contract is signed by both parties. If you're finishing training and matching into a Jacksonville fellowship, or you're an attending signed with one of the hospital systems here, that paperwork — not a pay stub — is your income file.
Who Qualifies for a Physician Loan in Florida?
The core eligible degrees are consistent across nearly every published program: MD, DO, DDS, and DMD, including residents, fellows, and interns holding those degrees with signed contracts. Truist adds DPM (podiatrists) to both its practicing and in-training tiers. Bank of America's published footprint covers doctors and dentists including residents and fellows.
Beyond that core, the lists diverge — and this is where shopping matters. Some programs extend eligibility to PharmD, DVM, OD, and DPM; at least one published program's eligible designations include CRNA, NP, and PA. Credit requirements vary too: minimum scores commonly start around 680, and the most aggressive tiers — 0% down at the highest loan amounts — generally require scores in the 700–720+ range. A few programs limit eligibility by years since training (one major bank's physician loan effectively requires doctors 15+ years out of training to be private-client customers). And while most national physician programs lend in Florida, not every one does, and caps differ by state and property type — these are primary-residence loans, typically single-unit homes and warrantable condos.
That patchwork is exactly why a physician should never take one bank's answer as the market's answer. One bank caps residents at a lower amount; another goes to $1,000,000. One excludes your student loans; another counts a percentage. As a mortgage broker, I shop your file across 200 lenders' programs — including multiple physician programs — against the actual program guidelines, not one bank's overlay.
What Are the Honest Trade-Offs of a Physician Loan?
A physician loan is not free money, and you should see the real numbers side by side. The trade-offs: the interest rate on a 0%-down physician loan often prices somewhat above the best conventional rate, because the lender is taking more risk with no PMI to insure it. Down-payment steps and caps vary by program and career stage. And it's a primary-residence product — no investment properties.
Here is an illustrative comparison on a $600,000 Jacksonville-area purchase, 30-year fixed terms, using example rates as of October 24, 2026 (Douglas Wilkerson, NMLS #1680719). The conventional example uses Freddie Mac's Primary Mortgage Market Survey average of 7.32% for the week ending October 22, 2026; the VA example uses the 6.96% VA 30-year average reported by Optimal Blue for October 21, 2026. These are illustrations to show structure, not quotes — your actual rate depends on your file.
| Structure | Cash Down | Loan Amount | Example Rate (30-Yr Fixed) | Monthly P&I | Monthly Insurance |
|---|---|---|---|---|---|
| Physician loan, 0% down | $0 | $600,000 | 7.50% | $4,195 | $0 — no PMI |
| Conventional, 5% down | $30,000 | $570,000 | 7.32% | $3,916 | ~$238 PMI (est.) until 20% equity |
| VA loan (veteran physicians), 0% down | $0 | $612,900* | 6.96% | $4,061 | $0 — no monthly insurance |
*VA loan amount includes the one-time VA funding fee of 2.15% ($12,900 on first use with no down payment) financed into the loan. Veterans receiving VA disability compensation are exempt from the funding fee entirely, which would drop both the loan amount and the payment.
Read the table the way an underwriter would. The conventional loan's principal-and-interest is lower — but it consumed $30,000 of your cash and adds roughly $238 a month in PMI (an estimate; actual PMI depends on credit and coverage) that protects the lender, not you, until you reach 20% equity. The physician loan keeps your cash in your accounts and deletes PMI permanently. And if you served — many physicians have, through HPSP scholarships and military residencies — the VA loan often beats both and deserves to be priced first. The right answer is the one with the lowest total cost over how long you'll actually own the home, and that answer changes file by file. That's a calculation, not a slogan — run it before you choose.
What Should a Physician in Jacksonville Do First?
Three things, in this order. First, don't wait out your residency or fellowship to start. If you have a signed contract — or you're about to — the home search can start now; waiting costs you a year or more of rent and a year of equity. Second, bring the right paper. Your signed employment contract or Match letter, your license, your student loan servicer statement showing your actual IDR payment or deferment status, and two months of bank statements. That packet is your entire underwriting story. Third, price the file more than one way. Get your numbers run through multiple physician programs and the conventional alternative (and VA, if you're eligible) on the same day, on the same purchase price, so you're comparing structures — not sales pitches.
Physicians: if a lender has already told you to "come back after you've worked a year and saved more," would you want to see what your signed contract already qualifies you for today?
Start Here
Take the free VA-Ready Score quiz to see where your file stands, or reach out and I'll price your contract across the physician programs and the conventional and VA alternatives — side by side, in dollars, before you sign a lease you don't need. More homebuying guidance lives at freemandouglas.com.
Douglas Wilkerson — NMLS #1680719
Direct: (904) 517-4049 | Office: (904) 906-8869
[email protected] | [email protected]
1548 the Greens Way, Ste. 4, Jacksonville Beach, FL 32250
Freeman Douglas Corporation is a DBA of Edge Home Finance. This is not a promise to lend — all credit decisions are subject to approval. Douglas Wilkerson, NMLS #1680719 | Edge Home Finance, NMLS #891464. Verify licensing at nmlsconsumeraccess.org. Equal Housing Opportunity.
